What Intraday Trailing Drawdown Actually Means
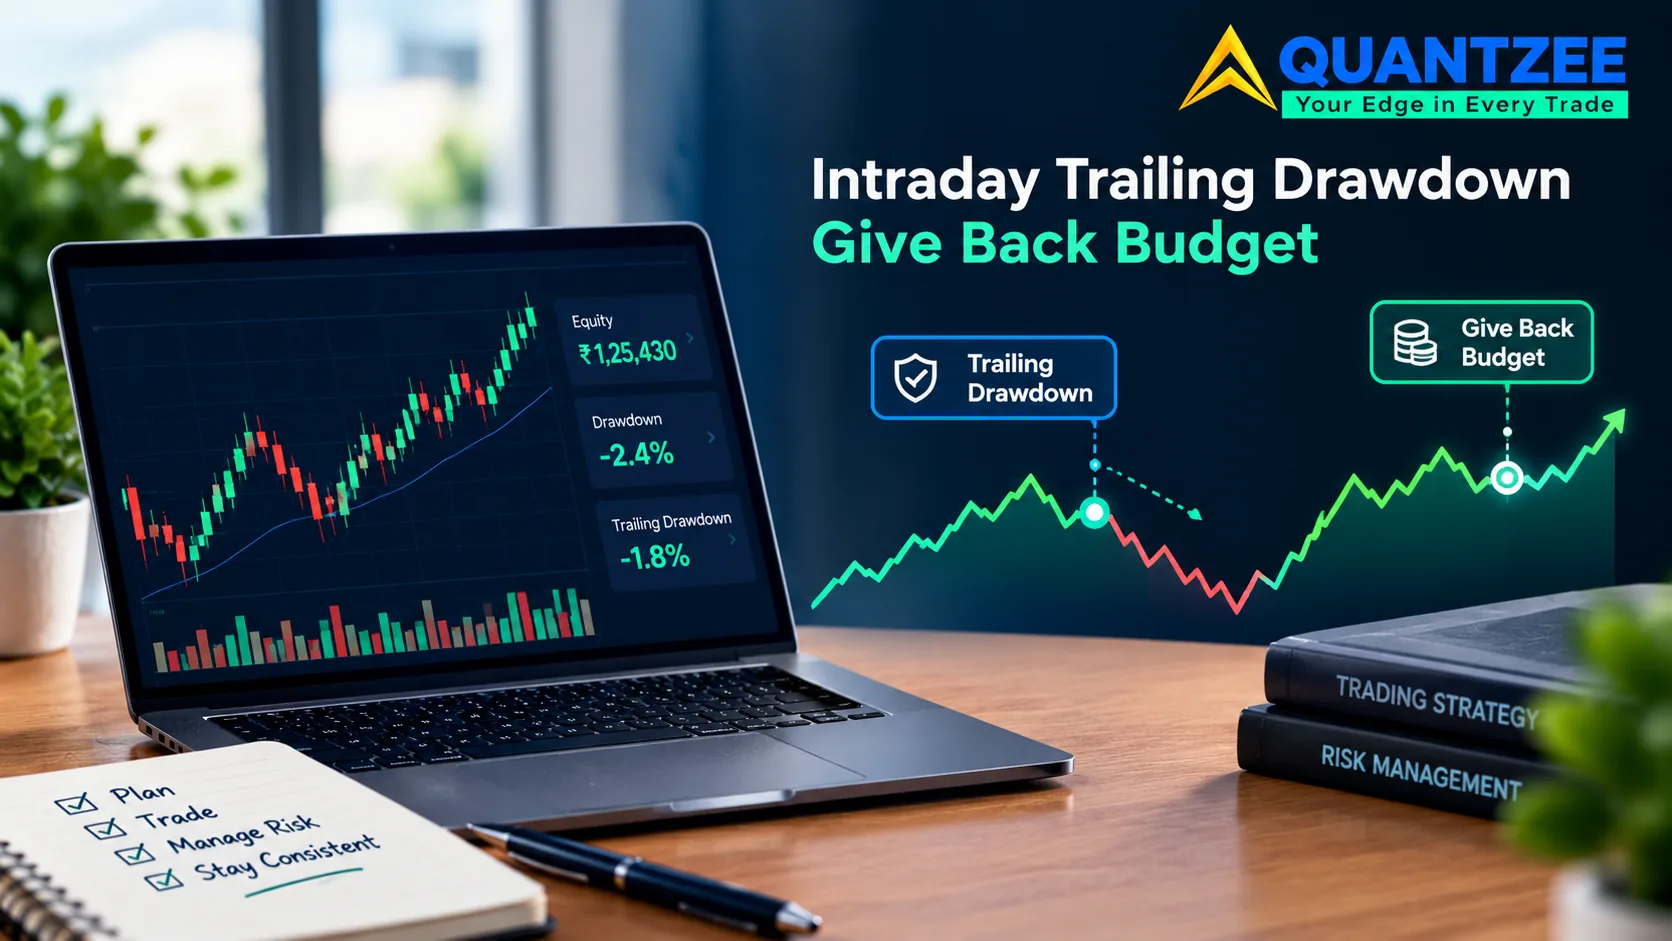
Intraday trailing drawdown is a loss limit that follows your unrealised equity, not just your closed-trade balance. The moment your account's open profit makes a new high during the trading day, the floor underneath you rises to match it. Give that profit back before the close and the floor doesn't fall with you — it stays where your peak left it. That is the whole mechanism in one sentence, and it is also the part most explainers skip past on their way to a bigger example.
What is intraday trailing drawdown in practice? It's the difference between a rule that watches your account balance at the end of each session and one that watches your equity tick-by-tick while positions are open. Trailing drawdown meaning, stripped of jargon: the most you're allowed to lose is measured from your best moment, not your starting point — and under the intraday variant, "your best moment" can happen mid-trade, before you've locked in a dollar of it.
Every page that covers this explains the mechanism. The quantvps.com piece on what a trailing drawdown is runs roughly 8,500 to 9,000 words and walks through the formula on $100,000 and $50,000 accounts in detail. None of the explainers convert the rule into a number a trader can actually use before the session starts: how much give-back per day the account can absorb before the floor catches up to current equity. That number is the point of this piece, and getting to it means starting from the two formulas underneath the rule.
The Two Formulas Behind Every Trailing Floor
Two equations run the whole system, and they rarely get stated as cleanly as they should be:
- Floor = Peak equity − Trailing distance. The floor is a fixed distance below the highest equity point you've touched, ever, since the account opened (or since the last reset, under some plans). It only moves one direction: up.
- Headroom = Current equity − Floor. This is what actually matters to you at any given second. It's the amount you can lose from right now before the account breaches. Headroom shrinks when equity falls and when the floor rises — and those two things can happen in the same minute if you're giving back an intraday peak.
Plug in numbers: a $50,000 account with a $2,500 trailing distance starts with a $2,500 floor and $0 headroom beyond the starting buffer. Push equity to a new peak of $53,200 intraday and the floor becomes $50,700. Fall back to $51,000 by the close and your headroom is $300 — not the $2,700 you'd have if the floor had stayed anchored to your starting balance. The trailing distance never changes. The floor's starting point does, and it only resets upward.
Equity vs. Balance: The One Setting That Changes Everything
Whether unrealised profit on an open position counts toward that peak is the single biggest fork in how any given account treats drawdown, and it's the first line to check in any rule book before you trade a cent on the account. Under an equity-based rule, a position that's $3,200 in the green the instant before you close it has already raised your floor by the full $3,200 — whether you take the profit or not. Under a balance-based rule, nothing moves until the trade is closed and booked.
This single setting is why two accounts with identical trade histories and identical trailing distances can end a week with wildly different buffers. futureshive.com's end-of-day versus intraday comparison, dated October 5, 2026, lays out a five-day table showing exactly this split: identical $3,200 gross profit across the week, and one accounting method leaves roughly $2,500 of buffer while the other leaves about $300. Same trades. Same P&L. The only variable is whether the peak was marked on unrealised equity or on the closed balance.
Three Variants, Side by Side
In practice, rule books fall into three camps:
- Intraday trailing on unrealised equity. The floor can rise mid-trade, on a position you haven't closed. This forgives nothing given back after the fact — a peak you touched for one tick still raised your floor.
- End-of-day trailing on the closed session balance. The floor only moves once per day, based on your balance after flattening. A big intraday swing that you don't carry into the close never touches the floor.
- Static. The floor is fixed from day one, usually at the starting balance minus the trailing distance, and it never moves again regardless of how high equity climbs.
Static is the most forgiving of the three for a trader who runs hot early and cold later — it never punishes a give-back, because there's no trailing floor to give back into. It's also the rarest structure on the accounts we've reviewed, because it gives the provider the least protection against a trader who gets lucky once and then blows up the lucky winnings plus the original stake.
Where the Floor Stops Climbing
Here's a detail that changes the arithmetic completely and gets stated far too rarely as a firm-specific rule rather than a universal one: many account types stop raising the floor once it reaches the starting balance plus a stated buffer. After that point, the floor is frozen — further peaks don't push it any higher. tradezella.com's trailing drawdown piece, updated May 19, 2026, calls this out as one of the "math traps" worth checking before you fund an account, and it's right to flag it as a trap, because traders routinely assume the floor keeps climbing forever.
Check this on your own provider's current rule page before you plan around it. It is not safe to assume either way — some accounts lock the trailing floor at breakeven-plus-buffer, others let it trail indefinitely toward your highest-ever peak. The two produce very different long-run behaviour on an account that's been profitable for months.
A Worked Day: Three Winners, One Loser, One Peak Given Back
Take a $100,000 account with a $3,000 trailing distance on unrealised equity. Starting floor: $97,000.
- Trade 1: +$900. Equity $100,900. New peak. Floor rises to $97,900.
- Trade 2: +$1,400. Equity $102,300. New peak. Floor rises to $99,300.
- Trade 3, still open: unrealised peak of +$1,100 mid-trade pushes equity to $103,400 for a few minutes. New peak. Floor rises to $100,400 — on money never realised.
- Trade 3 gives most of it back and closes at +$200. Equity falls to $102,500.
- Trade 4: −$500. Equity $102,000.
Closing equity: $102,000. Closing floor: $100,400 (set by the unrealised peak on trade 3, which the account never actually banked). Headroom at the close: $1,600.
When we run the same four trades under an end-of-day balance rule, the floor only moves once, at the close, from the day's final balance: $102,000 minus $3,000 equals $99,000 tomorrow's starting floor, with full $3,000 headroom available immediately. The intraday-equity trader gave up $1,400 of headroom to a peak they touched for minutes and never kept. That gap is the entire subject of this piece, expressed as one afternoon instead of a formula.
The Multi-Day Accumulation Effect
The single-day example understates the real problem, because the effect compounds. Buffer lost to a give-back never comes back — the floor doesn't fall just because equity fell after a peak, and it doesn't reset the next morning either, under most intraday-equity rule books. That means identical weekly gross profit can leave wildly different headroom depending on how many times, across the week, equity touched a high point it didn't hold.
futureshive.com's five-day table is the clearest public illustration of this on the page: five days, $3,200 of combined gross profit either way, one accounting method ending the week with roughly $2,500 of headroom intact and the other ending with about $300. The profit is identical. The number of intraday peaks that got given back before each day's close is what separates $2,500 from $300. A trader reading only the weekly P&L number — up $3,200 — would have no way to see that one version of their account is one bad day from a breach and the other has nearly a full trailing distance of room left.
The Give-Back Budget: How Much Peak You Can Afford to Hand Back
This is the number none of the explainer pages compute, and it's arithmetic, not a backtest, so it needs no historical data to show — just the account's own stated numbers.
Give-back budget for the day = (Current headroom) − (Minimum headroom you're willing to end the day holding).
Take a $3,000 trailing distance, a current headroom of $1,600, and a personal rule of never ending a session with less than $500 of room (a reasonable floor under a $3,000 distance, roughly one-sixth of it). The give-back budget for that session is $1,600 − $500 = $1,100. In plain terms: this account can touch a new intraday peak and then surrender up to $1,100 of it before the close and still end the day with the margin of safety you set for yourself. Touch a peak and give back $1,300 instead, and you've eaten into the $500 reserve you wanted to keep.
Run this calculation at the start of every session, not once. The inputs — current headroom and your personal minimum — change every day the floor moves, so a give-back budget computed last Tuesday tells you nothing about today.
What Changes in Position Management
Under an unrealised-peak rule, the usual playbook shifts in three specific ways. First, scaling out of winners early locks in realised profit, but it does not undo the floor having already risen on the unrealised peak you touched before scaling — the floor moved the instant equity made a new high, not when you booked the gain. Second, flattening everything before the close doesn't protect you from a floor that already climbed earlier in the session; it only stops you from giving back more after the peak. Third, and this surprises people the most: a trailing stop on the position itself does not solve this problem, it just interacts with it. A trailing stop decides when you exit a trade. The trailing drawdown rule decides where your account-level floor sits. Those are two different trailing mechanisms stacked on top of each other, and tightening the position's stop doesn't change what the account-level floor already locked in on the way up.
Rebuilding the Floor From Your Own Trade Log
This is the step none of the competitor pages show, and it's the one that lets you check a provider's dashboard instead of trusting it blind.
- Pull every fill from your trade log, ordered by timestamp, for the day or period in question.
- At each fill, compute running equity: starting balance plus realised P&L plus the mark-to-market value of any open position at that instant.
- Track the running maximum of that equity series. Every new high is a new peak.
- Apply the trailing distance to each new peak as it occurs: floor = that peak − distance.
- The floor at any point in time is the highest value that formula has produced so far — it only ever increases, never decreases, as you walk forward through the log.
- Compare your reconstructed floor against the one the dashboard reports. A mismatch tells you either the account uses a different variant than you assumed (end-of-day instead of intraday, or vice versa), or it's hit a stated breakeven-plus-buffer ceiling you hadn't accounted for.
In our experience walking through this with traders who were confused by a dashboard number, the mismatch is almost always one of those two causes, not a platform error. Our team built the position size calculator partly because traders kept asking for a way to check the account-level arithmetic against what a dashboard showed them, rather than taking either number on faith.
A Firm-by-Firm Snapshot — Read These Yourself Before You Trade
Terms on individual account providers change often enough that naming current limits from memory is a mistake no one should make in writing. According to the pages read for this piece — quantvps.com's trailing drawdown explainer (updated October 12, 2026), tradezella.com's trailing drawdown guide (updated May 19, 2026), and futureshive.com's end-of-day-versus-intraday comparison (dated October 5, 2026) — account types across the funded-account space use all three variants described above, and the specific trailing distance, buffer, and freeze point vary by provider and by account size tier within the same provider. None of that detail should be repeated here as if it were fixed; per the pages themselves, these terms are reviewed and revised on a schedule the providers set, not a schedule this article controls.
Confirm the current rule directly with your own account provider before you size a position against it. A rule you read about even a month ago may already be out of date on the provider's own current terms page.
Where the Formula Fits Into Broader Risk Management
None of this is specific to funded-account trading. The general discipline of measuring risk from a peak rather than a starting point, and of treating unrealised gains with the same caution as booked ones, shows up in mainstream investor education too. The SEC's investor education site, investor.gov, and FINRA's own investor center at finra.org/investors both frame prudent risk management around the same core idea: a gain you haven't locked in is not a gain you can spend, and sizing decisions should account for the full range of outcomes between your peak and your floor, not just the number on today's statement. That's a general principle, not a claim about how any specific funded-account provider's rule book is written — confirm the firm-specific numbers on the provider's own page, as covered above.
A trailing-equity floor is one specific case of a broader idea covered on Quantzee's max drawdown glossary page: drawdown measured from a peak rather than from a starting point, applied at whatever frequency the rule checks it. The same peak-to-trough logic that governs a funded account's trailing floor also governs how a strategy's own equity curve gets evaluated — see the companion piece on the house's equity curve simulator and drawdown distribution work, which looks at why a single historical drawdown figure understates the tail risk a strategy can actually produce. Both pieces come back to the same root lesson: a drawdown number taken from one peak, one path, or one week is a sample of size one, not the full picture.
Position sizing against a trailing floor also leans directly on the mechanics covered in Quantzee's position sizing glossary entry and risk-reward ratio glossary entry — a give-back budget of $1,100 means nothing without a position size small enough that one trade's adverse move can't blow through it in a single fill. A stop-loss set without reference to the day's give-back budget is sized for the trade, not for the account.
The Short Version
Here's the whole piece in a few plain lines. Your floor is your peak minus a fixed distance. The floor only moves up. If your account counts unrealised profit toward the peak, a trade you never closed can still raise the floor. Give that profit back and the floor doesn't follow you down. Check which rule your account uses. Check where the floor freezes, if it freezes at all. Then size your trades against the headroom you actually have left, not the number on last week's statement.