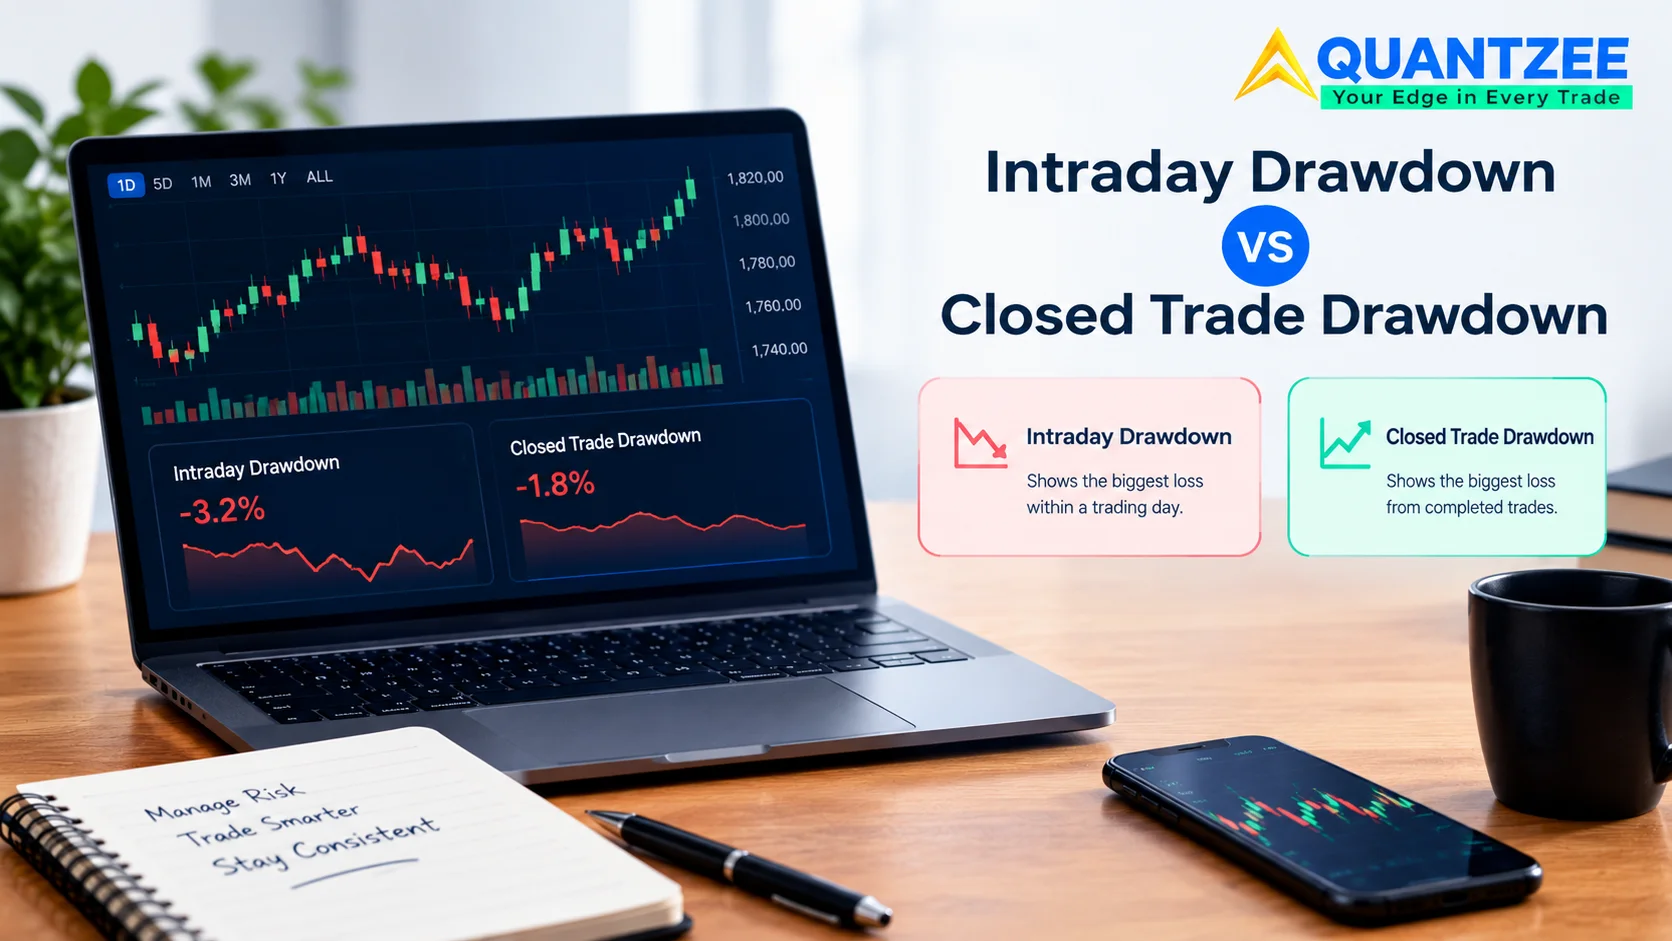
Run the same backtest through two reporting conventions and you can get two worst-case numbers that are several times apart, from the same trade list, on the same strategy. Intraday drawdown measures the worst mark-to-market loss while a position is still open, and it is almost never the number a vendor shows you by default. Closed-trade drawdown only looks at equity at the moment a trade exits, so it is blind to whatever happened while the position was live. According to the research split on this question, those two readings can disagree by a factor of two or more on an identical set of trades, and most platforms never state which one they used.
That gap matters. A strategy that looks calm on a closed-trade equity curve can be tripping stop-outs, margin calls, or an account's daily loss limit in between exits, and the closed-trade view will never show you that. This post walks through the three definitions in plain terms. It gives the formula behind each, and builds one small equity series you can check yourself so the disagreement stops being abstract. We built this breakdown at Quantzee because the question comes up constantly inside our own equity curve simulator and drawdown distribution tool, where users compare two or three readings of the same run and want to know why the numbers don't match.
Quantzee's analytical tools exist to make this kind of discrepancy visible rather than hidden inside a single summary statistic. The methodology below is the same one our drawdown distribution module uses under the hood, simplified down to one trade so the arithmetic is checkable by hand.
Three Definitions, One Word
"Drawdown" gets used for at least three different measurements, and per the academic literature on the topic, they are not interchangeable:
- Closed-trade (close-to-close) drawdown. Equity is sampled only at the moment each trade closes. Whatever happens between entry and exit is invisible — only the realized P&L at each exit counts toward the running curve.
- Bar-close mark-to-market drawdown. Equity is marked at the close of every bar (every 1-minute, 5-minute, or daily bar) while a position is open, not just at exits. This catches more of the path than closed-trade drawdown, but it still only samples at fixed intervals.
- Intraday (intrabar) worst excursion. The worst price the position actually touched while it was open, at tick resolution, between one bar close and the next. This is the deepest and most honest of the three, because it misses nothing.
A well-known community metric on one quant coding platform sidesteps the disagreement entirely. It takes the larger of the intraday and closed-trade readings. That is a tacit admission that the two numbers are expected to differ, sometimes by a wide margin, on the same strategy.
The academic literature treats maximum drawdown as a distribution, not a single fixed point. Atiya and Magdon-Ismail's paper on the maximum drawdown of discrete time processes derives the probability density of the worst drawdown a process is likely to show, which is the formal version of the same point this post makes informally: a single number can't capture what is really a range, and the sampling basis you pick determines where in that range your reported figure lands.
The Formula Behind Each Number
All three definitions share the same running-peak procedure. Only the sampling frequency changes.
- Track a running peak of equity, updated every time a new high is observed, using whichever sampling frequency the definition calls for (trade exits, bar closes, or ticks).
- At each new sample, compute the fall from that peak:
drawdown = (peak − current) / peak. - Keep the single largest fall observed over the full period. That largest fall is the maximum drawdown for that definition.
The formula never changes. What changes is how often you sample equity. That single choice is why three analysts running the same backtest through three tools can report three different "max drawdown" figures. Each one can be technically correct.
A Worked Equity Series You Can Check Yourself
Here is one trade, held across five 5-minute bars, on a $50,000 account. The exit comes in profit — which is exactly the case where the three definitions diverge the most, because a profitable exit can mask a brutal ride in between.
| Bar | Bar-close equity | Intrabar low (tick) |
|---|---|---|
| Bar 0 (entry) | $50,000 | — |
| Bar 1 | $50,420 | $50,180 |
| Bar 2 | $49,180 | $48,960 |
| Bar 3 | $48,650 | $47,900 |
| Bar 4 | $49,900 | $49,510 |
| Bar 5 (exit) | $51,300 | — |
Now run all three definitions against that one table:
- Closed-trade drawdown: 0%. Only two points exist in this view — the $50,000 entry and the $51,300 exit — and the trade closed above entry. A tool that only samples at exits will report this trade as having no drawdown at all.
- Bar-close drawdown: 3.51%. The running peak across bar closes is $50,420 (Bar 1). The trough after that peak is $48,650 (Bar 3).
(50,420 − 48,650) / 50,420 = 3.51%. - Intraday (tick) drawdown: 5.00%. The same peak of $50,420 against the intrabar low of $47,900 inside Bar 3.
(50,420 − 47,900) / 50,420 = 5.00%.
Three honest readings of the identical trade, ranging from "no drawdown" to "5% gone," depending only on how often equity was sampled. Scale that one trade up to a multi-month backtest with hundreds of trades and the gap between the closed-trade figure and the tick-level figure routinely grows into multiples, not fractions of a percent.
Why Bar Size and Tick Data Change the Number Again
Bar-close drawdown is not a fixed number either — it moves with the bar size you choose. Mark the same strategy on 5-minute bars and on 1-minute bars and you will get two different maximum drawdown figures, because a finer bar catches more of the intrabar path than a coarser one. Move to tick data and the figure moves again, usually larger, because ticks are the finest sampling available and catch wicks that even 1-minute bars smooth over.
This is the part vendors rarely disclose. A report that says “max drawdown: 4.2%” without naming the bar size is not wrong, exactly — it is simply incomplete, and the number quietly depends on a choice the reader never saw. Our tick data vs. bar data glossary entry covers this trade-off from the data side if you want the mechanics of why finer data always pulls drawdown figures down (deeper), never up.
Peak-to-Trough on the Curve vs Worst Excursion Inside One Trade
These are two different questions, and conflating them is the single most common mistake we see in strategy write-ups:
Peak-to-trough drawdown on the equity curve asks: across the whole backtest, what is the worst fall from any prior high to any later low, regardless of trade boundaries? This is the number that answers "how bad does the account get" over the strategy's full run.
Worst excursion inside a single trade (sometimes called maximum adverse excursion, or MAE) asks a narrower question: on this one trade, how far underwater did it go before it recovered or was closed? A strategy can have a small peak-to-trough curve drawdown and still carry individual trades with brutal MAE, if winners and losers happen to offset each other on the aggregate curve while individual positions take a beating along the way.
Both numbers matter, and they answer different risks. Peak-to-trough tells you what your account statement would have shown an outside observer. MAE tells you what it actually felt like to hold the position, and it is the number that determines whether a stop, a margin call, or a risk desk's intervention would have fired before the trade had a chance to recover.
Which Number to Compare Against a Margin Call or a Loss Limit
If you are checking a strategy against a hard constraint — an account's daily loss limit, a broker's margin maintenance level, or a prop firm's maximum drawdown rule — the closed-trade figure is the wrong number to use, every time. Those constraints are enforced in real time against your mark-to-market equity, not against your realized P&L at exit. A margin call does not wait for you to close the trade first.
The bar-close figure is closer, but still a sampled approximation. The intraday (tick) figure is the only one of the three that tells you whether a given loss limit would actually have been breached during the trade, because it is the only one that sees the full path rather than a sampled slice of it. If a strategy’s reported drawdown is the closed-trade number and you are stress-testing it against a hard account rule, you are comparing the wrong two numbers and the comparison will flatter the strategy every single time.
Why the Smaller Number Always Flatters a Strategy
There is no scenario in which closed-trade drawdown reads deeper than bar-close drawdown. There is no scenario in which bar-close reads deeper than the tick-level figure. The ordering is structural, not a quirk of any particular backtest. Finer sampling can only reveal more of the path, never less. So whenever a strategy report quotes a single "max drawdown" figure with no definition attached, assume it is the smallest of the three available readings. That is the one most reporting tools default to, and the one least likely to scare off a buyer.
The fix is not complicated. When a report quotes one number with no definition, ask three questions before trusting it: what was sampled (trade exits, bar closes, or ticks), what bar size was used if bar-close, and were open positions marked to market at all or only counted once they closed. Any report that cannot answer those three questions is not giving you a drawdown figure — it is giving you a number that happens to be labeled “drawdown.”
A Reporting Rule Worth Adopting
We built our own equity-curve and drawdown-distribution work around a simple rule, and it is worth adopting whenever you publish or receive a drawdown figure: print the definition next to the number, state the bar size if one applies, and state plainly whether open positions were marked to market or only counted at close. Three short facts, attached to every figure, and the ambiguity this whole post exists to resolve disappears.
Per the stress-testing checklist we maintain for strategy review, this same discipline — naming your sampling basis before quoting a risk number — applies just as directly to drawdown as it does to any other stress metric. A number without its measurement basis attached is not a fact; it is a guess dressed up as one.
CFA Institute has made a version of this same argument from the portfolio-construction side. Its piece on sculpting portfolios around maximum drawdown introduces conditional drawdown at risk, a measure built from the mean of the worst slice of drawdowns rather than a single peak-to-trough figure, precisely because one number compresses too much information to be a reliable risk control on its own. The same caution applies at the strategy level: one quoted figure, with no basis attached, compresses three structurally different measurements into a single misleading digit.
How This Differs From the Account-Rule Version of "Drawdown"
If you landed here looking for how a funded-account or prop-firm drawdown rule is calculated against a trailing or static threshold, that is a related but separate question from the one this post answers. This article is about measuring drawdown as a strategy-performance metric across a backtest or live track record; an account-rule page is about a specific contractual threshold a firm enforces against your balance in real time. Our max drawdown glossary entry is the right jumping-off point if the account-rule question is what actually brought you here, and working out your own give-back budget under a trailing floor goes further into the specific formulas — together they link out to reporting-metric, account-rule and give-back-budget context rather than merging them into one page, which is why we kept this piece narrowly on the measurement question.
For readers comparing a strategy's own reported drawdown against what it would have shown on live fills rather than a backtest, our note on the backtest-vs-live mismatch covers the second, equally common way a quoted drawdown number ends up smaller than reality: slippage and fill assumptions in the backtest itself, independent of which of the three definitions above was used.
The methodology in this post works for any strategy where you can access both the trade list and the intrabar price path — options, futures, or equities, on any timeframe. The worked series above used round numbers on purpose so the arithmetic is checkable in under a minute; the same three-definition gap shows up, usually larger, across a full multi-year backtest.
For where each number appears in TradingView's Strategy report and how to read the report as a whole, see how to backtest a TradingView indicator.