We read a sample of five of the highest-ranking strangle options guides before writing this one, and the pattern repeats across all five: the same payoff diagram, an out-of-the-money call, an out-of-the-money put, two breakeven lines sitting outside the strikes. What almost none of them price is the four fills it takes to get in and out of that position, and what those fills do to a wing strike where the order book is thinnest. If you have read five articles on strangle options this month and still don't know how much of your edge your broker's quote screen is quietly taking, that gap is the reason, and it's the gap this piece closes.
A strangle is one call and one put on the same underlying, same expiration, struck away from the current price in opposite directions. Buy both legs and you own a long strangle; sell both and you're short one. Either way, the position's delta sits close to zero the moment you put it on, because a call's positive delta and a put's negative delta roughly cancel at the strikes a strangle typically uses. That's the entire construction. The disagreement in the options-education world isn't over what a strangle is — it's over what it actually costs you to run one, and almost nobody writes that part down.
What Is a Strangle in Options, Exactly?
The textbook definition: one out-of-the-money call plus one out-of-the-money put, same underlying, same expiration, different strikes. A straddle uses matching at-the-money strikes for both legs; a strangle deliberately moves both legs further from the current price, which is why a strangle costs less to open — the options are cheaper the further they sit from the money — but needs a bigger move to pay off, because the price has further to travel before either leg finishes in-the-money.
Both legs lose value to time decay if the underlying sits still, and both legs are non-directional bets on the size of a move rather than its direction. A long strangle wants the underlying to travel far enough, in either direction, to clear one of the two strikes plus what you paid. A short strangle wants the opposite: the underlying stays inside a range wide enough to let both legs expire worthless, or close to it.
Breakeven Math, Worked Both Ways
The formula is the same shape on both sides of the trade — only the arithmetic sign flips on who keeps the premium.
Long strangle: upper breakeven = call strike + total premium paid. Lower breakeven = put strike − total premium paid.
Short strangle: upper breakeven = call strike + total premium collected. Lower breakeven = put strike − total premium collected.
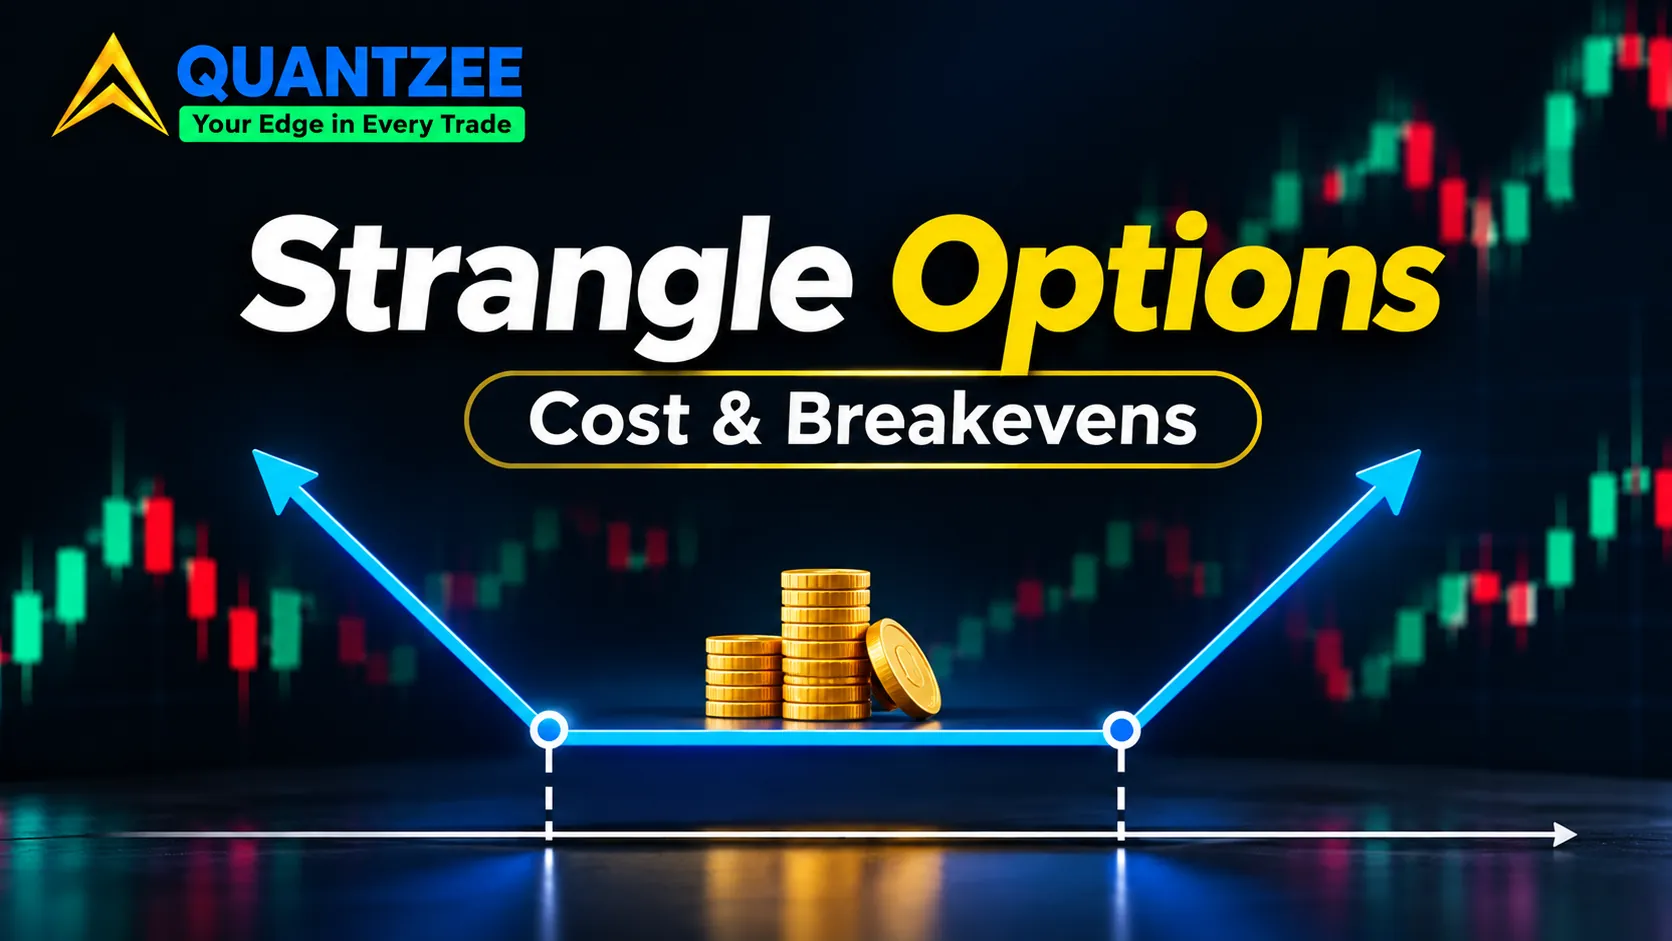
Take a clearly hypothetical underlying at $500. You buy the 520 call and the 480 put, 30 days to expiration, and the two legs together cost $6.00. Upper breakeven is 520 + 6 = $526. Lower breakeven is 480 − 6 = $474. The stock has to close outside that $474–$526 band by expiration for the long strangle to show a profit — anywhere inside it and at least one leg is worth less than what you paid for both.
Flip it short. You sell the same 520 call and 480 put and collect the same $6.00 in total premium. Now your breakevens are identical in number — 526 on the upside, 474 on the downside — but the trade wins on the opposite condition. You profit if the underlying stays inside $474–$526 through expiration, and you lose once it closes beyond either line. Same strikes, same premium, same two numbers on the page, and a completely inverted bet. That mirror is worth sitting with before the cost section. The rest of this piece explains how execution cost moves those two lines — and it moves them in opposite directions depending on which side of the trade you're on.
The Cost Section Every Strangle Article Skips
Here is the arithmetic that almost never makes it into a strangle write-up. A strangle is four fills per round trip — buy the call, buy the put, then later sell the call, sell the put (or the mirror, for a short position) — and every one of those four fills crosses a bid-ask spread. The articles that walk through breakeven math almost always price every leg at the midpoint, as if your order fills exactly between the bid and the ask every time. Pull up a real quote screen and that's rarely what happens, especially on the strikes a strangle actually uses.
Spreads widen the further a strike sits from the money, and a strangle is built entirely out of out-of-the-money strikes — the thinnest part of the chain. On a liquid large-cap index option, an at-the-money contract might show a nickel-wide spread. Move out to the 16-delta strikes a short strangle commonly uses and that same name can show a spread two to four times as wide. Fewer market makers actively quote size that far out, and the ones who do widen their own quote to cover their own risk. When we pulled a live SPY chain in early November 2026 purely to check this, the at-the-money contracts were quoting roughly a nickel wide, and the 16-delta wings were showing $0.15–$0.20. That's a snapshot on one ordinary session, not a measured average — but directionally exactly what the market-structure logic predicts.
Express that spread as a share of the premium you're actually trading, not as a raw number, and the distortion gets obvious fast. A $0.15 spread on a $0.60 wing option is a quarter of the premium. The same $0.15 spread on a $6.00 at-the-money option is two and a half percent. Cross that spread at the worst side instead of the midpoint — buy at the ask, sell at the bid, on all four legs — and a position quoted at a tidy $6.00 total premium can bleed 10–20% of that premium to execution alone. The underlying hasn't moved a single cent yet. That's not a rounding error. The entire thesis of a short strangle is "collect premium and let time do the work," so giving back a fifth of the premium to the spread is giving back a fifth of your entire edge before the trade has had one day to work.
This is also where the breakeven lines from the section above stop being fixed. On a long strangle, the cost of crossing four spreads effectively raises your entry price, which widens the band the underlying has to clear — your real breakevens sit further out than the textbook $474–$526 example. On a short strangle, the same cost eats into the premium you actually banked, which narrows the band you're protected inside — your real breakevens sit closer together than the quoted premium implies. Same four fills, same direction of cost, and it pushes the two trade types' breakevens apart from each other rather than moving them the same way.
Delta Picks Your Strikes — and Your Breakeven Width — at the Same Time
Delta measures how much an option's price moves for a one-dollar move in the underlying, and a near-the-money option's delta sits close to ±0.5 while a deep out-of-the-money option's delta approaches zero. That's the textbook definition. In practice, delta is also close to the market's own estimate of the odds that strike finishes in-the-money by expiration — a 16-delta call is one the market is pricing at roughly a 16% chance of landing in-the-money, all else equal. Almost nobody connects that second reading back to the breakeven math. It matters because the moment you pick strikes by delta, you have also picked your breakeven width — the market set that price for you.
Walk one hypothetical underlying through three delta choices and watch what moves together. At 30 delta, the strikes sit closer to the money, the premium collected is higher, and the breakeven band is narrower — the market is telling you a move past either strike is relatively more likely, and it's charging you more to take the other side of that bet. At 16 delta, strikes sit further out, premium collected drops, and the breakeven band widens — the market sees a lower chance of the underlying reaching either strike, so it pays you less to sell that insurance. Push to 10 delta and the pattern continues: even less premium, an even wider band, an even lower priced-in chance of the move happening. Until it does. And because the strike was so far out, the loss when it arrives is large relative to the thin premium collected for taking that side.
That's the trade-off in one sentence: a wider breakeven band bought with delta always comes with less premium funding that protection, and a narrower band funded with more premium always comes with less room for the underlying to move before you're underwater. There is no delta choice that gives you both a wide cushion and a fat premium — the market already priced that contradiction out.
Reading the Expected Move, and What Cost Does to It
One already-established method, and a genuinely useful one, is to read the expiration's expected move straight off the at-the-money straddle price — add the call premium and the put premium at the at-the-money strike, and that sum is a rough one-standard-deviation estimate of how far the market expects the underlying to travel by expiration. It's the same idea underneath the more formal calculation — expected move equals the underlying price multiplied by implied volatility multiplied by the square root of days to expiry divided by 365 — just read directly off live quotes instead of computed from an IV figure. If you trade S&P 500 options, the VIX gives you the same expected-move number in one step, as worked through in our volatility index guide.
Lay your strangle's two breakevens on either side of that expected-move estimate and you get a quick read on whether the structure is priced generously or tightly relative to where the market itself expects the underlying to land. A short strangle with breakevens comfortably outside the expected move is being sold at a premium that, on the market's own math, has room to spare. One with breakevens sitting inside the expected move is pricing in less cushion than the market's own volatility estimate would suggest is comfortable.
Here's the piece that estimate alone leaves out: the execution cost from the section above moves both lines before you've measured anything. On a long strangle, crossing four spreads at the unfavorable side pushes your real breakevens further apart than the clean textbook number, which eats directly into the room you have relative to the expected move. On a short strangle, that same cost pulls your real breakevens closer together, which eats into your cushion from the other direction. Compare your strangle to the expected move using the quoted premium only, and you're comparing against a number that's already drifted by the time your fills clear.
Long and Short Strangles Are Different Bets, Not Two Variants of One Trade
Treating long and short strangles as the "buy version" and "sell version" of the same idea undersells how differently they behave. A long strangle needs the underlying to move further than what you paid, and it wants to be entered when implied volatility is low and has room to rise — a cheap straddle-equivalent premium with volatility likely to expand works in the buyer's favor twice over, once from the move and once from the IV itself inflating the option's value before expiration arrives. A short strangle needs the opposite: the underlying staying inside what you collected, entered when implied volatility is elevated and more likely to fall than rise, so that time decay and a shrinking IV premium both work in the seller's favor.
Tie each side to the IV direction it needs and the two trades stop looking like mirror images. A long strangle bought right before an earnings date, when implied volatility is already elevated, is fighting an IV crush on top of needing a large move. That's a much harder bet than buying the same structure when volatility is cheap and likely to expand into an uncertain catalyst. A short strangle sold into that same elevated pre-event volatility is positioned correctly for the IV side of the trade — provided the position size and risk tolerance can survive the realized move that catalyst might actually produce.
The Short Strangle's Open-Ended Risk, and What an Iron Condor Does About It
A short strangle's risk profile is asymmetric in a way that deserves to be stated plainly rather than buried in a risk-disclosure footnote. The short put's loss is bounded — the underlying can only fall to zero, so the maximum loss on that leg is capped, however large. The short call's loss is theoretically open-ended, because there is no ceiling on how high the underlying can rise before expiration. Margin gets held against both legs for exactly this reason, and that margin requirement is usually the first real constraint a trader runs into with this structure, well before the position itself is threatened.
Assignment risk sits alongside that open-ended exposure. If either short leg finishes in-the-money at expiration, the holder of the long option on the other side can exercise, and you're assigned the underlying shares — short if it was your call, long if it was your put. Early assignment is rare on standard American-style equity and index options outside of a dividend date or a deep in-the-money situation, but it is not impossible, and a short strangle carries that exposure on two legs simultaneously rather than one.
An iron condor is the defined-risk evolution of exactly this structure: keep the same short call and short put, and buy a further out-of-the-money call and a further out-of-the-money put against them. Those two long legs cap the loss on both sides at a known, fixed maximum — the price of that protection is a smaller net premium collected than the naked strangle would have brought in. The trade you're making is explicit: give up some income for a maximum loss you know on day one instead of an exposure that, on the call side, has no defined ceiling. For the mechanics of how the two extra legs change the margin and payoff math, the iron condor glossary entry covers the structure in full rather than repeating it here.
Managing a Strangle Is Arithmetic, Not Intuition
Two mechanical choices do almost all the work of shaping how a short strangle's outcomes distribute: the profit target and the stop. Closing at roughly half the credit collected — buying back the strangle once it's worth half what you sold it for — locks in a partial win early and gets you out of further time-decay exposure well before expiration, in exchange for giving up the second half of the potential profit on trades that would have gone to zero on their own. A stop set at some multiple of the credit collected — closing once the position is worth two or three times what you took in — caps how much a single losing trade can cost relative to how much a single winning trade pays, which is the entire mechanism behind managing a position whose maximum loss on the call side is otherwise open-ended.
That pair of rules is also the honest explanation for why a short strangle's reported win rate tends to run high. Closing winners early at half credit converts trades that would eventually expire worthless anyway into booked wins sooner, while a defined stop caps how much any single loser subtracts from the tally — the combination mechanically inflates the win percentage relative to a strategy held to expiration with no exits at all. A high win rate on a short strangle is the designed output of the exit rules, not independent evidence that the underlying thesis is sound. A reported number without the profit target, the stop, the days-to-expiration, the delta the strikes were chosen at, the position size, and the cost assumption behind it carries close to no information at all, because any of those five levers can move the win rate substantially on its own.
How to Read the Strangle Numbers Already Circulating Online
The most frequently cited real numbers for short strangles trace back to two sources. According to a Panoptic Research review of a one-year stretch from May 2024 through April 2025, short strangles recorded a 68.22% daily win rate against 70.96% for short straddles over the same period, with a +1.25% median monthly return against +1.80%, and a −11.1% max drawdown against −13.7%. Separately, a projectfinance study covering eleven years of SPY data, run at 16 delta and 60 days to expiration, reports that the structure held up across that sample — and the study itself notes its figures are "before fees and taxes," a disclosure most pages quoting the number drop on the way to a tidy headline.
Neither of those studies, as reported, discloses the entry and exit rules, the position sizing, or the slippage model behind its figures — which means the numbers are not reproducible from what's published, however widely they get repeated. Before trusting any short-strangle win rate or return figure you come across — including the two above — the minimum disclosure list to demand is: the exact rule set for entry and exit, the instrument traded, the date range and sample size, the delta and days-to-expiration used, the position sizing, and the cost model applied to fills. Missing any one of those six, the number is a headline, not a result you can evaluate.
None of that is a reason to dismiss the structure — short strangles are a standard, widely used income strategy for a reason. It's a reason to read the next statistic you see about one the way you'd read any other unaudited claim: useful as a starting point, not as a verdict.
Frequently Asked Questions
Originally published November 4, 2026.
Strike selection by delta, expected-move reads, and the IV context behind every trade are exactly what a dashboard needs to surface in real time rather than require manual lookup — see Quantzee's roundup of TradingView indicators for options traders for the volatility, open-interest, and trend tools that make this kind of pre-trade checking faster on the chart itself. For the underlying mechanics referenced above, the straddle vs strangle glossary entry, the implied volatility and theta decay entries, and the broader options Greeks reference cover each piece in more depth. Quantzee's tools are built for analysis and education, not advice — always paper trade a new structure before sizing it with real capital, and treat every bid-ask figure above as a snapshot on one ordinary session, not a promise of what your own fill will look like. For a deeper look at assignment and exercise mechanics specifically, the Options Industry Council's options education resource maintains a detailed reference that goes further than this piece has room for.
For the Indian cost stack on top of the spread (STT at 0.15% of premium since April 2026, exchange charges, GST), see the worked NIFTY round trip in our NSE options guide.