Every page on the rho greeks says the same thing: rho is the forgotten greek, and it's small. Almost none of them put a number on "small." This post does. We priced one at-the-money call across seven expiries, from one week to two years, and set the dollar effect of a 25 basis point rate move next to one day of theta and one volatility point of vega. On the 7-day contract, one day of decay is worth about 32 times the quarter-point rate effect. By 74 days to expiry the two are even, and past that point rho is the bigger number. That crossover is the whole story, and it's computed, not guessed.
Quantzee builds analytical tools for TradingView users, and the Greeks come up constantly when people ask what an option's price is actually sensitive to. The options Greeks glossary entry defines rho in a few lines. This article goes further: it prices it.
What Rho Measures, in the Unit That Matters
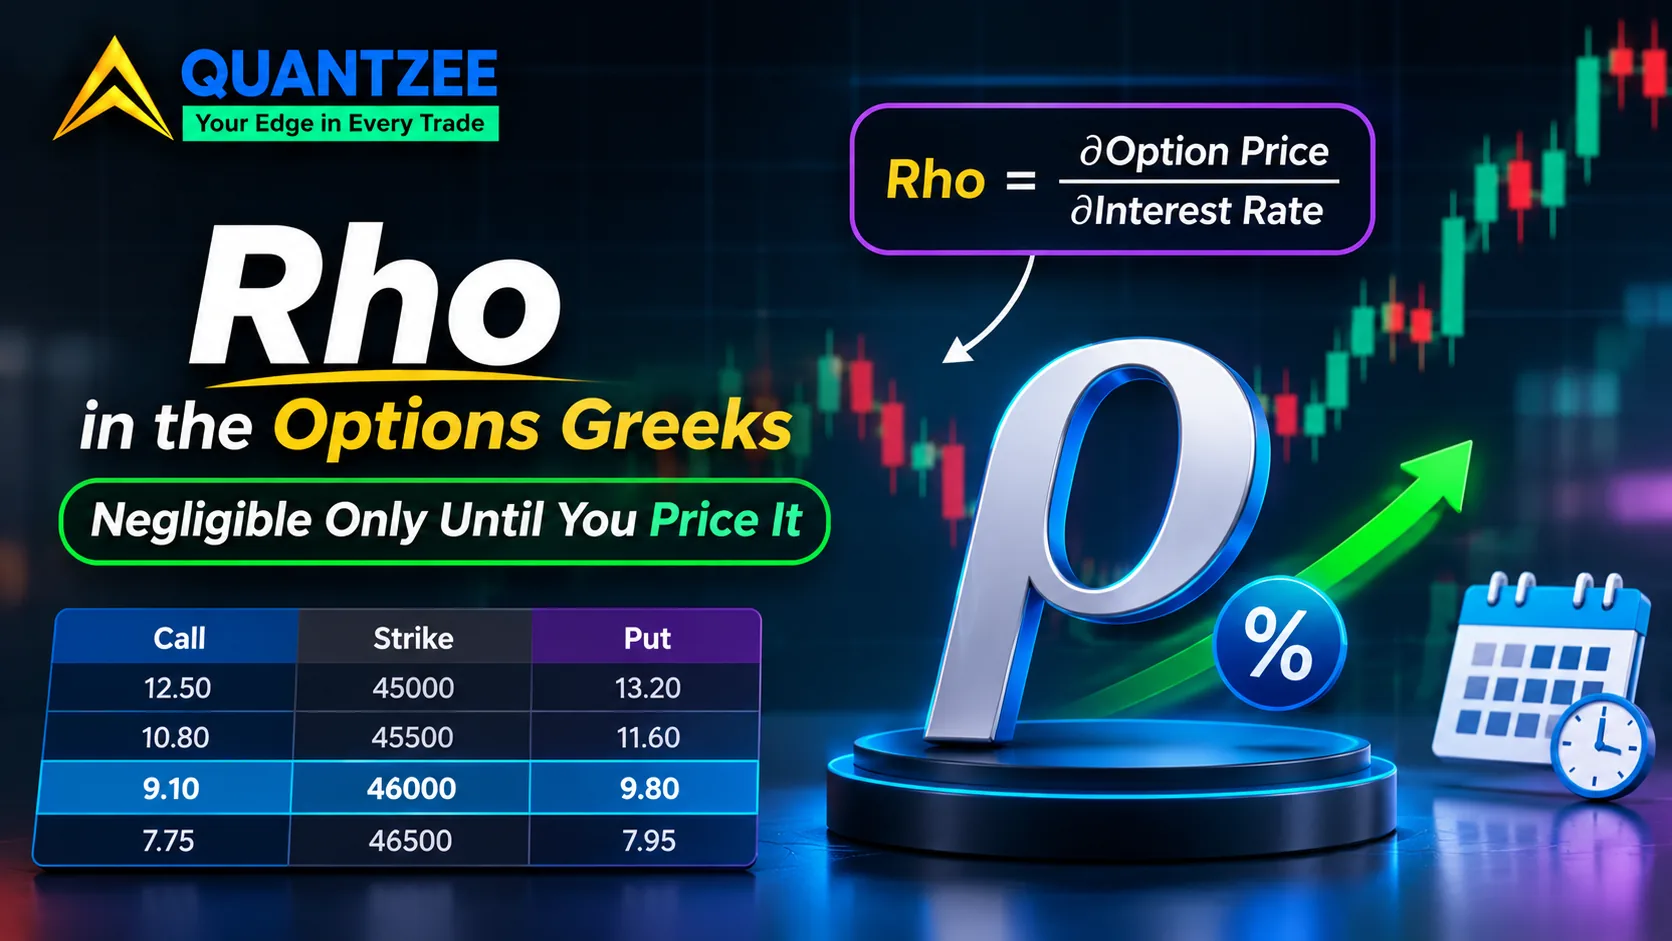
Rho is the change in an option's value for a one percentage point move in the interest rate. A rho of 3.03 on a call means the call gains $3.03 per share if the rate rises by one point and everything else holds still. Multiply by 100 for the standard equity contract and you get $303.
One point is a clumsy unit. Central banks don't move in one-point steps very often; they move in quarter points. According to the Federal Reserve's published meeting calendar at federalreserve.gov, the FOMC holds eight scheduled meetings a year, so the rate input to your pricing model gets, at most, eight scheduled chances to step. A realistic rate move is 25 basis points, a quarter of the rho figure on your screen. Every number in this article uses that quarter-point version unless it says otherwise.
Why Call Rho Is Positive and Put Rho Is Negative
You don't need to memorize the signs. The strike is a payment you make in the future, and its present value depends on the discount rate. Higher rates shrink the present value of that payment.
For a call, the strike is what you pay to take the shares. A smaller present cost of paying it makes the right to buy more valuable, so call rho is positive. For a put, the strike is what you receive. A smaller present value of that receipt makes the right to sell worth less, so put rho is negative. The formula for a European call carries the term K·T·e−rT·N(d2), and that K·T product is the discounting horizon at work.
The Two Levers: Time to Expiry and Moneyness
Rho behaves like a bond's duration. The longer the money is tied up, the more a rate change matters. Rho grows roughly in line with time to expiry, which is why a 2-year contract carries about 100 times the rho of a 1-week one even though nothing else about the position changed.
Moneyness is the second lever. Deep in-the-money calls behave like stock bought on credit: you hold exposure to the shares while deferring most of the payment, and the deferred strike is what rate moves reprice. Far out-of-the-money options have small exercise probabilities, so N(d2) shrinks and so does rho. Those two levers, time and moneyness, are all you need to anticipate where rho will be large, much as strike and expiry drive market-wide gamma exposure models of dealer hedging.
How We Built the Comparison (Methodology and Inputs)
Here's the part the competing pages skip. Our methodology is plain formula arithmetic on stated inputs. We built the table from the Black-Scholes-Merton model with a continuous dividend yield, the standard European-option closed form. Nothing here is a live quote, and this is not a measurement of any market. It's a reproducible calculation on a modelled contract, so you can check every figure.
- Underlying: a $600 index ETF, modelled on a SPY-style product (the spot price is an assumed input, not today's quote)
- Strike: $600, at the money
- Implied volatility: 18% (assumed, held constant across expiries)
- Interest rate: 4.0% (assumed)
- Dividend yield: 1.2% (assumed)
- Greeks per share; multiply by 100 for one contract. Theta is per calendar day, vega per one volatility point, rho per 25 basis points
One more caveat before the numbers. Holding implied volatility flat across expiries is a simplification, because real term structures slope. We chose it so that time to expiry is the only thing changing down the table. In the last section we show how the answer moves when volatility changes.
The Table: 25 Basis Points Against a Day of Theta and a Point of Vega
Dollar figures are for one contract (100 shares), at-the-money call, using the inputs above. Rho is for a 25 basis point rise in rates.
| Days to expiry | Call price | Rho (+25 bp) | Theta (1 day) | Vega (1 vol pt) |
|---|---|---|---|---|
| 7 | $613 | +$1.40 | −$44.90 | +$33.10 |
| 30 | $1,303 | +$6.20 | −$22.80 | +$68.40 |
| 60 | $1,880 | +$12.50 | −$16.70 | +$96.40 |
| 90 | $2,337 | +$18.80 | −$14.00 | +$117.60 |
| 180 | $3,412 | +$37.60 | −$10.50 | +$164.60 |
| 365 | $5,062 | +$75.80 | −$7.80 | +$229.50 |
| 730 | $7,505 | +$148.70 | −$5.90 | +$311.10 |
Three things stand out when you read across the rows.
First, on the weekly contract, the quarter-point rate effect is $1.40. One day of decay costs $44.90. If you're holding a position that expires in seven days, a rate decision is lost in the noise of a single afternoon. The "negligible" label is fair there.
Second, the sign flips in dominance. Rho rises from $1.40 to $148.70 as expiry moves out, while theta falls from $44.90 to $5.90. At 365 days, a quarter-point move is worth about ten times a day of theta.
Third, rho never beats vega on this at-the-money ladder. Even at two years, one volatility point ($311.10) is worth more than 25 basis points of rate ($148.70). Rates matter more over time, but implied volatility stays the larger lever for a standard at-the-money position. If a source tells you rho eventually "dominates" an at-the-money option, check its arithmetic.
The Crossover: 74 Days
For this contract, the quarter-point rate effect exceeds one day of theta at about 74 days to expiry. At 60 days rho is $12.50 against theta at $16.70. At 90 days it's $18.80 against $14.00. The crossing sits between them, and solving for it directly puts it at 74.
The put side crosses sooner, at about 61 days, because at-the-money put theta is smaller than call theta in this setup. The rate-and-dividend carry in the formula lifts one and trims the other.
That number isn't universal. It depends on what you feed the model, and the next section shows how far it moves.
What Moves the Crossover
We reran the at-the-money call crossover with one input changed at a time. Everything else stayed at the table's values.
- Rate at 3.0% instead of 4.0%: crossover at about 72 days
- Rate at 5.0%: about 76 days
- Implied volatility at 12%: about 57 days
- Implied volatility at 30%: about 103 days
The rate level barely matters. Volatility matters a lot. Higher implied volatility inflates theta, because options with more time value to lose lose more each day, and that pushes the crossover out. Calm markets pull it in. So "rho starts to matter after roughly two to three months" is a decent rule for at-the-money options at ordinary volatility, and it stretches past three months when implied volatility is high.
Moneyness moves it more than anything. We repeated the calculation for a deep in-the-money call, strike $450 against the same $600 spot. That contract has almost no time value, so its theta is only about $3 a day, and the quarter-point rate effect passes it in about 10 days. Rho on a deep in-the-money call isn't a footnote. It's the larger of the two from nearly the first week.
A Worked Reading: What the Table Means for Three Holding Periods
Numbers in a table only help if you can map them onto a position, so here are three readings of the same data. None of them is a trade idea. They show how to read the rows.
A trader holding the 7-day call for two days is exposed to roughly $90 of decay against about $1.40 of rho on a quarter-point move. Rates aren't part of that position's story. The 90-day call held for the same two days sees about $28 of decay against $18.80 of rho per quarter point, so a surprise at a policy meeting could plausibly matter about as much as the decay itself. And the 365-day call held for two days loses about $15.60 to theta while carrying $75.80 of rho exposure per quarter point. There, a rate surprise is the larger risk by a wide margin, and only a volatility move beats it.
The same logic applies to puts with the sign reversed. A long-dated put loses value when rates rise, so rate hikes help the call and hurt the put even when the underlying doesn't move at all. When we compared call and put rows at the same expiry, the put's rho at 365 days was −$68.30 per quarter point against +$75.80 for the call. The asymmetry comes from the dividend yield in the carry term.
Where Rho Genuinely Binds in Practice
Three situations are worth checking rho before you place anything.
Long-dated single-leg options. A one- or two-year call or put is where the table shows rho at $75 to $150 per contract per quarter point. If you're comparing a long-dated option's price movement with the underlying's move and something doesn't add up, a rate change is a candidate for the gap.
Deep in-the-money calls held as stock substitutes. The $450 call above carries a rho of about $1.03 per share per quarter point at one year and $1.85 at two. That's the cost of financing the deferred strike, and it's embedded in the premium.
Multi-leg structures that don't net out. A calendar or diagonal spread has legs with different expiries. Short-dated legs carry little rho and long-dated legs carry a lot, so the structure ends up with a net rate exposure you didn't deliberately choose. A same-expiry vertical spread nets most of it away, because both legs discount over the same horizon.
For shorter-dated work, such as weeklies, the practical rule is simple. Read theta decay and implied volatility first. They dominate the P&L of short contracts, and our guide to volatility index options covers how the volatility side is usually read.
The Observable Part: Scheduled Meetings and the Forward Curve
Rho is unusual among the Greeks because part of its input path is public. Central banks publish their meeting calendars in advance, and the forward curve shows what the market prices for future policy rates. Per the Fed's own calendar, the dates of the eight scheduled FOMC meetings are known a year ahead.
That lets you ask a bounded question: does a known rate event fall inside this contract's life? A 7-day option that spans a meeting still has only $1.40 of rho per quarter point, so the answer barely matters. A 365-day option spans all eight, and each quarter-point step is worth about $76 per contract on the table above.
What it doesn't let you do is conclude anything about direction. Knowing a meeting is scheduled says nothing about the decision, and nothing in this article is a view on where rates are going. The calendar tells you when the input can change. It doesn't tell you which way.
The Dividend Interaction
On an equity option, the carry in the pricing formula is the rate minus the dividend yield, not the rate alone. That's why our inputs include a 1.2% yield. A rate rise and a dividend-yield rise partly offset in the carry term, which is why two otherwise identical underlyings can show different effective sensitivity to the same policy move.
The practical consequence: when you read a rho value off a broker platform, you're reading a number that already blends both inputs. A stock with a high yield will show a rho that looks muted for its expiry, and the rate isn't the reason.
The Honest Limit: Rho Is a Model Sensitivity
Everything above is a derivative of one formula. Black-Scholes-Merton assumes a single constant rate for the whole life of the option, a flat curve, European exercise and constant volatility. Real equity options are American-style and real rate curves aren't flat, so a platform's rho will differ from ours, sometimes by a visible amount at long expiries.
Treat the table as a map of relative size, not a forecast of what your fills will do. The ratio between rho and theta at a given expiry is strong. The third decimal isn't. The Options Industry Council at optionseducation.org publishes the standard strategy material if you want to see how each structure's Greek profile is described by the clearing-house educators. Data from the model is only as good as its inputs, and the inputs here were chosen to be explicit, not to be market-accurate.
If you track Greeks visually on TradingView, our list of TradingView indicators for options traders covers the chart-side tools. And since rate-sensitive positions often track open interest in the longer-dated strikes, that's a sensible next read. All of this is analytical software output and education, not advice or a recommendation to trade anything.
Reproduce It Yourself
The calculation is short. For a European call with spot S, strike K, rate r, yield q, volatility σ and time T in years:
d1 = (ln(S/K) + (r - q + σ²/2)·T) / (σ·√T)
d2 = d1 - σ·√T
rho (per 1 pt) = K·T·e^(-rT)·N(d2) / 100
vega (per 1 vol pt) = S·e^(-qT)·n(d1)·√T / 100
theta (per day) = [-S·e^(-qT)·n(d1)·σ/(2√T) - r·K·e^(-rT)·N(d2) + q·S·e^(-qT)·N(d1)] / 365
Multiply rho by 0.25 for the quarter-point version. Put in the table's inputs and you'll get the same rows. Put in your own and you'll find your own crossover, which is the useful version of this article.