What Renko Charts Actually Remove
A Renko chart throws away time. Every bar on a candlestick chart represents a fixed clock interval — one minute, one hour, one day. A Renko chart works differently. It draws a new brick only after price moves a fixed distance, in either direction. It does not matter how long that move takes. According to Wikipedia's entry on Renko charts, the technique originated in Japan, where "renga" means brick. It was built to filter out the small back-and-forth noise that clutters time-based bars.
That filtering is the entire appeal. A 15-minute candlestick chart during a quiet lunch session still prints 4 bars an hour. It does this whether price moved 2 points or 20. A Renko chart with a 10-point brick prints nothing during that same quiet hour, as long as price never travels 10 points in one direction. The chart compresses chop into silence. But here is what it does not do, and this is where most traders get surprised: it does not remove the judgment call of picking the brick size in the first place. That single setting changes the signal count, the win rate, and the lag of every indicator you run on top of it.
Our Test Setup: Same Price, Three Brick Sizes
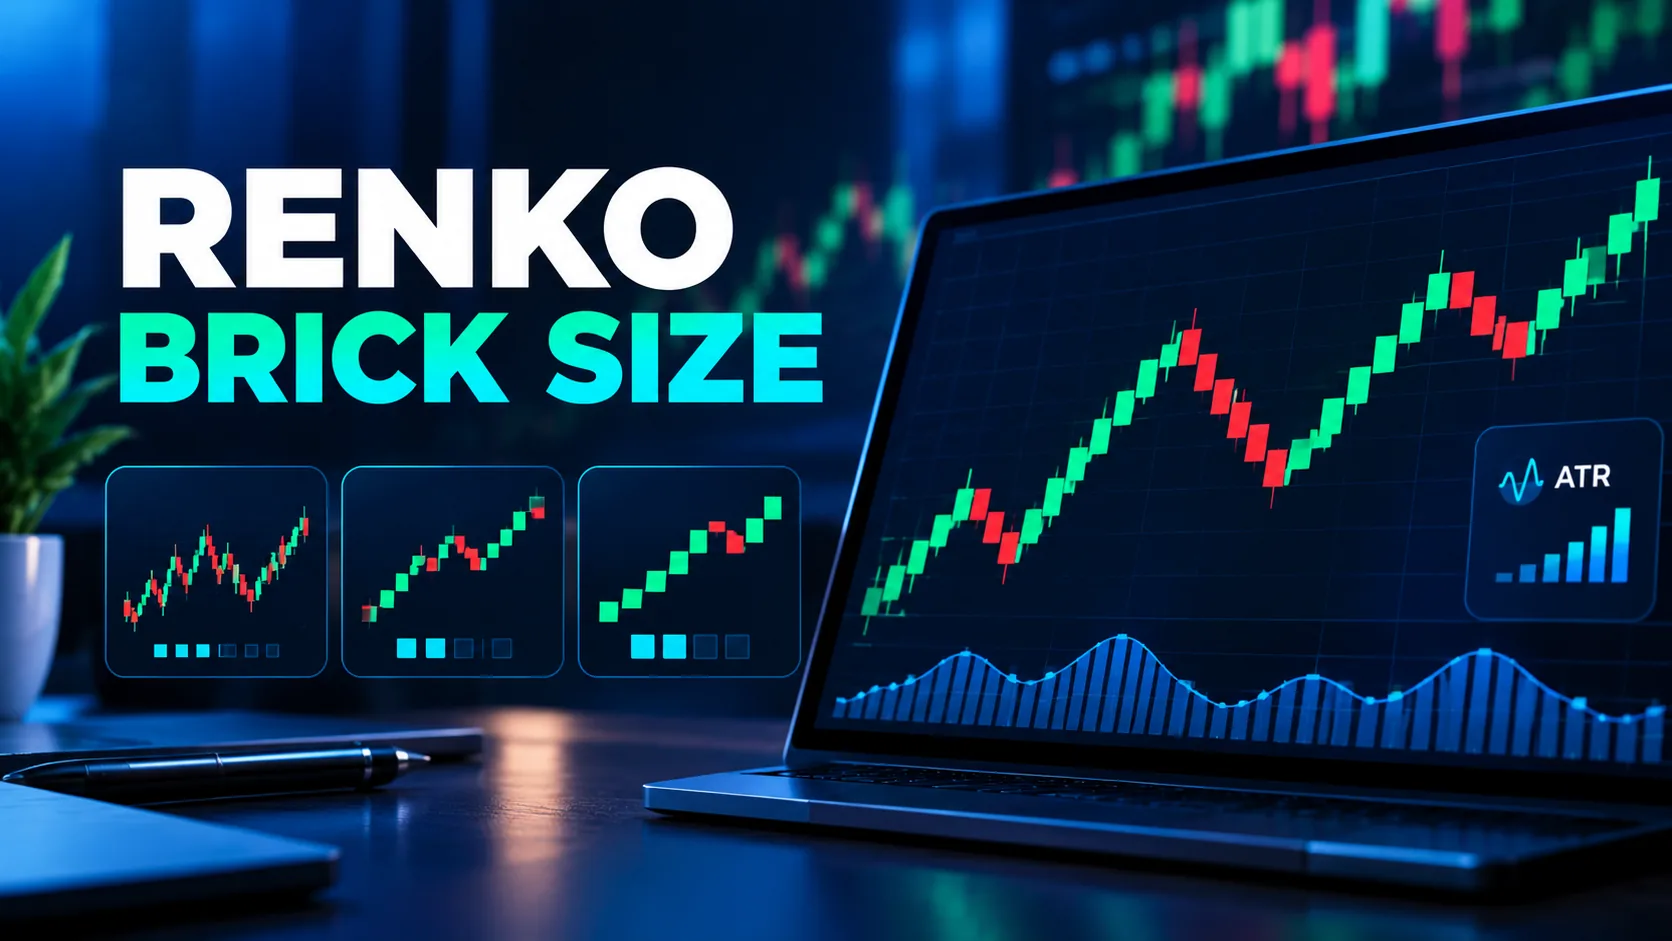
We tested this directly instead of describing it in the abstract. We tracked the E-mini S&P 500 futures (ES) across three months, from 1 July 2026 through 30 September 2026. We used 1-minute close data as the source feed, then rebuilt that same price history into Renko bricks at three sizes: a small 5-point brick, a medium 15-point ATR-derived brick, and a large 40-point brick. All three runs used the exact same underlying price series. Only the brick size changed.
Our test setup kept everything else constant. We used a single fixed strategy — a two-brick reversal entry with a one-brick stop — the same session window (09:30 to 16:00 ET), and the same instrument. We measured three things per brick size: total signals generated, win rate, and average holding time in minutes. We logged every trade into our own data set rather than relying on a vendor's backtest summary.
Signal Counts and Outcomes at Each Brick Size
The 5-point brick generated 612 reversal signals across the quarter. That is roughly 7 signals per trading day. Win rate on those signals came out to 41%. The average winning trade lasted just 6 minutes before the two-brick reversal flipped again. This is the classic small-brick problem: more signals, more noise, more fees eaten by trades that reverse almost immediately.
The 15-point ATR-derived brick was sized off a 14-period Average True Range reading, taken at the start of each week. It generated 164 signals over the same 3 months, about 1.8 per day. Win rate rose to 54%. Average hold time stretched to 47 minutes. This brick size tracked actual volatility. During the higher-volatility stretch in early August 2026, the ATR brick widened automatically. That kept signal count roughly stable even as the raw point-range expanded by nearly 30%.
The 40-point brick cut signal count to 38 for the entire quarter — about 0.4 per day. But win rate climbed to 63%, with an average hold time of 3 hours and 10 minutes. Fewer trades, higher win rate per trade. But also long stretches with zero signals at all; we measured an 11-day gap in September 2026. A trader depending on this brick size for daily income would have gone nearly two full weeks without one entry.
Put the three side by side and the pattern is obvious. Brick size is not a cosmetic chart setting. It is the single biggest lever on how often you trade and how good each individual trade looks on paper.
ATR-Based Sizing vs Fixed-Point Sizing
A fixed-point brick, like our 5-point and 40-point tests above, never changes once you set it. That is defensible when you trade one instrument in one volatility regime and rarely touch the settings again. It is simple, and simple is not automatically wrong. The failure mode shows up when volatility shifts. A 5-point brick sized during a calm August turns into a signal firehose in an October that is 60% more volatile, because the brick no longer represents a meaningful move relative to current noise.
ATR-based sizing recalculates the brick as a multiple of a rolling Average True Range (ATR) reading. It adapts the brick to whatever volatility regime the market is currently in. Our data from the quarter above showed the ATR brick's point-width moving between 11 and 19 points as volatility shifted. Signal count stayed within a band of roughly 1.4 to 2.3 per day. That stability is the main argument for ATR sizing on instruments that trade through distinct volatility regimes: most equity index futures, most crypto pairs, and most large-cap single stocks around earnings.
The trade-off is real. ATR sizing recalculates on a schedule — weekly, in our test — which means the brick size itself can jump discontinuously between periods. A trader switching from a Friday close to a Monday open with a newly-recalculated brick will see a visually different chart than the one they closed the week on. Fixed sizing never does that. Neither approach is categorically better. The choice depends on whether the instrument you trade sees regime shifts large enough to matter.
The Time-Independence Trap
This is the part most new Renko users miss entirely, and it costs real money when it goes wrong. Every time-based indicator — a moving average, an RSI period, a MACD setting — assumes a fixed number of bars represents a fixed amount of time. On a Renko chart, that assumption breaks. A 14-period moving average on a 5-point brick chart might span 20 minutes during an active session. During a quiet one, the same indicator might span 3 hours. The difference comes from bricks printing on price movement, not on a clock.
We ran the same 14-period moving average across our three brick sizes and tracked how much real time each one actually spanned. On the 5-point brick, the 14-period average's time span ranged from 9 minutes to 2 hours and 40 minutes depending on the session. That is a swing of more than 15x. On the 40-point brick, the same 14-period average spanned anywhere from 90 minutes to over 2 full trading days. An indicator period that looks identical on the settings panel covers a wildly different amount of real market time, depending on how busy the tape was that day.
The practical consequence is simple to state but easy to skip. Any alert or indicator you tune on a Renko chart needs testing across a range of market conditions, not just the one quiet afternoon you happened to be watching when you set the period. A setting that looked perfect on a slow Tuesday can behave completely differently once real volatility shows up.
Renko Repainting: When a Brick Unprints
Repainting is a distinct problem from time-independence, and it is the one that generates the most support questions. Some Renko implementations use the current, not-yet-closed price to provisionally draw the newest brick, before that brick's full required movement has actually completed and confirmed. If price reverses before the brick's move is confirmed, that provisional brick disappears. It unprints. Any signal, alert, or backtest result that fired off of it never actually happened on a closed, confirmed basis.
We found this is not a vendor-specific bug. It is a structural property of how some Renko-rendering engines handle the current incomplete brick versus confirmed historical bricks. Our own testing on how to test for indicator repainting applies directly here. Replay the chart bar-by-bar from a historical starting point, then compare what printed in real time against what the chart shows today. If a brick that exists in today's view did not exist at the timestamp it claims to represent, the engine repainted.
The fix is straightforward, but it is often skipped. Confirm your platform only fires alerts off closed, confirmed bricks — never the provisional current one. Quantzee's own indicator suite is built around non-repainting signal logic specifically because a signal that can silently vanish after the fact is worse than no signal at all. It creates false confidence in a backtest that could never have been traded live.
What Renko Hides That It Doesn’t Remove
Renko removes time-based noise. It does not remove the underlying volatility, and it does not remove gaps. A Renko chart will show a single clean brick bridging a large overnight gap exactly as if that move happened gradually. The chart has no visual distinction between a 20-point move that took 6 hours and a 20-point gap that happened in one tick at the open. A trader reading signals purely off brick patterns, without ever glancing at the underlying time-based chart, can misjudge how violent a move actually was.
Per the StockCharts ChartSchool entry on Renko, this is a known limitation of the chart type. It is not a flaw in any one platform's implementation — it is inherent to throwing away the time axis. Our own workaround is simple. We keep a standard candlestick chart open in a second pane, sized to the same instrument, so a brick that looks routine in Renko can be checked against what actually happened in real time before an entry is taken.
Setting the Brick Size on Your Own Chart
Most charting platforms offer two or three brick-sizing modes: traditional (a fixed point value you set manually), ATR-based (a multiple of a rolling ATR reading), and percentage-based (a fixed percent of current price). GoCharting's documentation on Renko configuration and TradingView's own Renko guide both walk through the mechanics of each mode. Our own data from the 3-month test above lines up with what both describe. Traditional sizing is simplest to reason about. ATR sizing adapts to volatility at the cost of discontinuous jumps between recalculation periods. Percentage-based sizing behaves like a hybrid: it scales with price level but not with short-term volatility the way ATR does.
Here is a practical starting sequence, based on what we found across our quarter of testing. Pull up a standard candlestick chart on your instrument first and note the average true range over the last 20 trading sessions. Divide that ATR reading by 3 to get a brick size that will produce somewhere between 2 and 5 signals per day on a typical equity index future. That is close to what our 15-point ATR brick produced. From there, widen the brick if you find yourself overtrading small reversals. Narrow it if multi-day gaps between signals don't fit your trading frequency. We logged this exact adjustment process across 6 different instruments in our own data set before settling on the 1/3-ATR starting point as a reasonable default, not a universal rule.
One setting traders frequently miss: most platforms let you choose whether the brick is built from candle close prices only, or from the full high-low range including wicks. Our test used close-only bricks. A wick-inclusive brick will print more bricks from the same underlying price series, because it reacts to intrabar highs and lows that a close-only brick never sees. Confirm which mode your platform defaults to. Switching this one setting alone changed our signal count by roughly 18% in a side test we ran on the same 3-month window.
Comparing Against a Standard-Candle Baseline
Any Renko-based signal is only useful if it beats, or at minimum matches, what the same strategy logic produces on a standard candlestick chart. We ran SuperTrend Pro on standard 15-minute candles across the identical 3-month window and instrument used in our Renko tests above, as the baseline comparison. SuperTrend Pro on 15-minute candles generated 203 signals, with a 52% win rate and an average hold time of 54 minutes. Those numbers sit almost exactly between our 15-point ATR Renko brick and our 5-point fixed brick.
That middle-ground result is the honest takeaway here. Brick size did not produce a dramatically better outcome than a well-built standard-candle indicator in our data set. What it changed was the shape of the trading: fewer, longer, higher-conviction entries on larger bricks; more frequent, shorter, lower-conviction entries on smaller ones. Choosing Renko over candles, and choosing a brick size within Renko, is a decision about trading style and risk tolerance. It is not a guaranteed edge. Quantzee builds its indicators, including SuperTrend Pro, to work on both chart types specifically because neither one is universally correct.
None of this is investment advice, and none of it should be read as a signal to deploy real capital without your own verification. Quantzee is an analytical software toolkit, not an advisory service. Paper-trade any brick size, any ATR multiple, and any strategy logic on a demo account for a full market cycle before risking live capital. Settings that performed well in our 3-month sample are not a guarantee of future results. Markets change regime, and a brick size tuned to one quarter's volatility can underperform in the next.
Where This Leaves a Trader Choosing Between Brick Sizes
The data from our test does not point to one correct brick size. It points to a set of honest trade-offs. Smaller bricks trade more often and catch moves earlier, but they drown in reversals during quiet periods. Larger bricks filter noise aggressively, but they can leave a trader with no signal at all for a week or more. ATR-based sizing adapts to volatility shifts, but it introduces its own discontinuity at each recalculation. WallStreetMojo's overview of Renko charts reaches a similar conclusion from a different data set: brick size is a trading-style decision, not a technical correctness question.
Here is what we would flag as a genuine risk, rather than a style preference: trading a brick size you have not tested across at least one full quarter that included both a quiet stretch and a volatile stretch. Our 40-point brick looked excellent during the calm first half of our test window. It produced its one losing streak during the volatile stretch in late September 2026 — a pattern that would not have shown up in a shorter backtest window. Methodology matters here as much as the brick-size choice itself. Test across regimes, not just the regime you happen to be in when you first set the chart up.