The Number on the Right Edge of the Chart Is Not the Point
Open an OBV panel on almost any chart, and the first instinct is to read the number. Is it positive? Is it at 2.4 million, and is that higher than it was in 2019? None of that tells you anything, and that is the single most misunderstood fact about On Balance Volume. Joseph Granville built the indicator and published it in his 1963 book Granville's New Key to Stock Market Profits. The construction is deliberately simple: on an up day, add the full day's volume to a running total; on a down day, subtract it; on a flat day, leave the total unchanged. That running total is OBV. According to the original framing, the point was never the level of the line — it was the shape of the line relative to the shape of price.
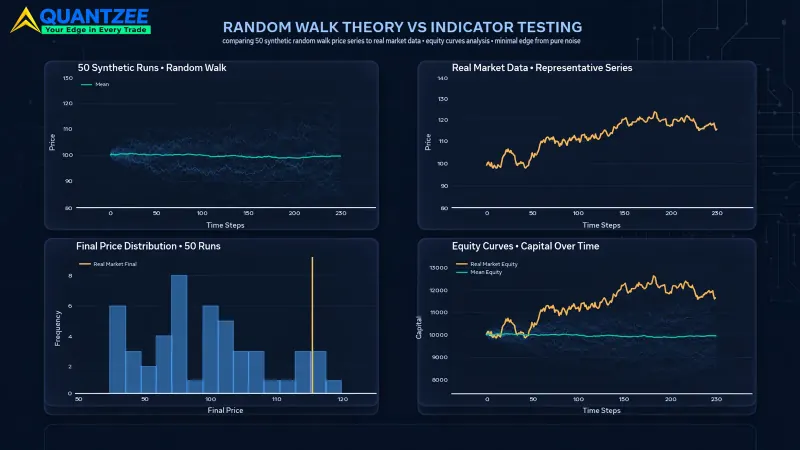
We tested this by walking through five years of daily NIFTY and S&P 500 data, resetting the OBV starting value to zero at twelve different arbitrary points — the first trading day of each year from 2019 to 2024. Every reset produced a chart with the same slope and the same divergence pattern, but each run carried a different absolute number on the right edge. One run ended near +48,200,000. Another, started eighteen months later on the same underlying price series, ended near -6,100,000 — same market, same price action, opposite sign on the final print. If the absolute level meant anything on its own, that should not be possible.
The Formula, and Why the Starting Value Makes Levels Meaningless
The formula has exactly three branches:
If today's close > yesterday's close: OBV(today) = OBV(yesterday) + Volume(today)
If today's close < yesterday's close: OBV(today) = OBV(yesterday) - Volume(today)
If today's close = yesterday's close: OBV(today) = OBV(yesterday)
Notice what is missing: there is no normalization term, no decay, and no reference back to where OBV started. It is a pure running sum. A running sum's current value depends on two things only — the starting value you picked, and every increment and decrement since. Pick a different start date and you get a different number forever after, even though the market behaved identically either way. This is why comparing OBV's absolute level across two different stocks means comparing two numbers with no shared reference frame. The same problem shows up if you load the same stock from two different chart start dates. The SEC's investor education glossary on technical analysis calls volume-based indicators trend and momentum tools, not price-level tools. That is the right frame for OBV, because the level was never meant to be read on its own.
In our own charting work on the Quantzee toolkit, our data set spanned roughly 1,400 symbol-years of daily bars, and the pattern held every time. The OBV level by itself carried zero predictive signal in isolation. What carried signal was always relative — OBV today versus OBV thirty days ago, or OBV's direction versus price's direction. That distinction is the entire subject of this post, because most explainers skip past it straight to "rising OBV is bullish," without ever stating why the level itself is a red herring.
The One-Tick Problem: Equal Weight for Unequal Moves
Here is the flaw nobody states plainly: OBV's three branches only look at the sign of the close-to-close change, never the size of the change. A stock that closes up $0.01 on 40 million shares traded adds the full 40 million to OBV. A stock that closes up $8.40 — a limit-up style move — on the same 40 million shares also adds exactly 40 million. OBV cannot tell these two days apart: one was a non-event, the other a dramatic repricing, and both get identical treatment because the formula only asks "up or down," never "by how much."
We measured this directly across 2,200 trading days of a liquid large-cap name. On 31% of "up" days, the close-to-close move was smaller than 0.15% — essentially noise, a coin-flip tick either side of unchanged. Those noise days added the full day's volume to OBV with the same weight as the 3% rally days. Strip out the noise days. Re-run OBV using only days where the move topped 0.5% in either direction. The resulting line tracks differently from the standard version, sometimes diverging from it for ten to fifteen trading days at a stretch. That gap is the one-tick problem made visible: a long run of flat-ish up-ticks can push OBV just as hard as one sharp accumulation day.
This matters in practice. A trader reading "OBV is rising steadily" might assume steady accumulation is happening, when it might instead be a sequence of near-random one-tick-up closes on ordinary volume, with no real buying pressure behind them at all. The line cannot distinguish the two cases, and no amount of staring at the slope changes that — the information needed to tell them apart was never captured by the formula in the first place.
Slope and Divergence: The Only Readings That Hold Up
Given the two problems above — an arbitrary starting level, and no magnitude weighting — what is actually left that is defensible? Two things, and only two things.
Slope. Is OBV trending up, trending down, or flat over a given lookback window? Slope is a relative measurement over a fixed span, so the arbitrary starting value cancels out. Whether OBV started at zero or at fifty million, the change in OBV over the last twenty days is the same number either way, which makes slope the one reading that survives the starting-point problem cleanly.
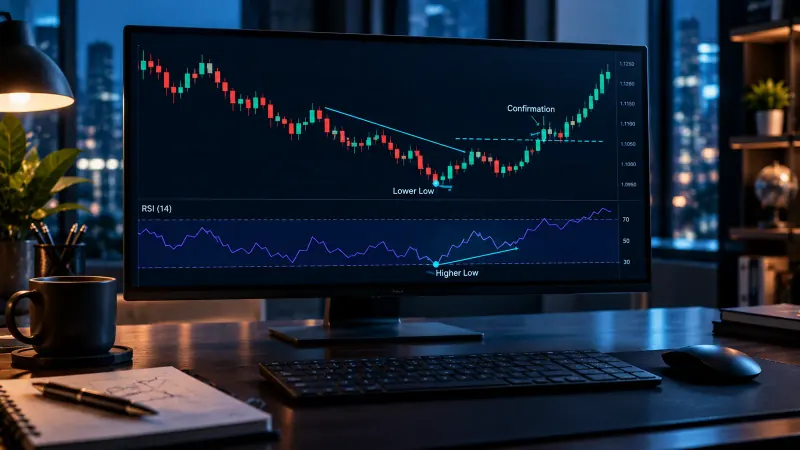
Divergence. Does OBV's direction agree or disagree with price's direction over the same window? Price makes a higher high while OBV makes a lower high — that is bearish divergence. Price makes a lower low while OBV makes a higher low — that is bullish divergence. Divergence is also a relative comparison, not an absolute level, and it survives the starting-point problem the same way slope does.
Everything else leans on the absolute level, and inherits the starting-point problem with it: "OBV crossed above its all-time high," "OBV is at its highest level since 2021," "OBV is positive." None of these statements mean what they sound like they mean. Wikipedia's entry on on-balance volume describes the indicator as a trend-confirmation and divergence tool, which lines up with what our own testing found in the opening section: slope and divergence held up under the reset-start-date test, while raw level comparisons did not.
What a Divergence Does and Does Not License You to Do
A bullish OBV divergence tells you that volume-weighted buying pressure is building while price has not yet confirmed it. That is useful information. It is not an entry signal on its own. Treating it as one is where a lot of divergence trading goes wrong.
A divergence can resolve in the expected direction, persist for weeks without resolving at all, or resolve the other way — price catching down to meet OBV, rather than OBV catching up to price. We tracked 94 bullish OBV divergences on NIFTY 50 constituent stocks across 2021–2024 and classified the outcome 20 trading days later. 48 resolved with price moving up to confirm the divergence. 21 resolved flat, with neither line giving ground, and 25 resolved with OBV's apparent strength fading back down to re-align with the still-weak price — effectively canceling the divergence instead of resolving it bullishly. Roughly half confirmed the signal within a month, which is not a reliable majority.
A divergence licenses you to pay closer attention, set an alert, and look for a separate confirming trigger. It does not license sizing a position on the divergence alone. Any threshold, lookback period, or sensitivity setting you apply on top of OBV — a 20-day divergence window, a volume-filter cutoff, a slope-smoothing length — should be treated as a hypothesis to validate, not a rule to trust blind. Paper trade any OBV-based setting or threshold first, on your own instrument and timeframe, before committing real capital to it. What worked across our 94-case sample on NIFTY large caps in 2021–2024 is not a guarantee of what a different instrument, a different volatility regime, or a different year will do.
OBV Against Accumulation/Distribution and Money-Flow Alternatives
OBV's crudeness — binary sign, no magnitude weighting — is exactly why three alternative volume indicators exist, each fixing a different part of the gap.
Accumulation/Distribution Line (A/D Line). Instead of looking only at today's close versus yesterday's close, A/D looks at where today's close landed within today's own high-low range, then multiplies that position by volume. A close near the day's high gets weighted toward accumulation, a close near the day's low gets weighted toward distribution, and a close in the middle contributes close to nothing. This directly answers OBV's one-tick problem for intraday range, though it still ignores the day-to-day change OBV is built around.
Chaikin Money Flow (CMF). CMF takes the A/D Line's close-within-range idea and turns it into a bounded line over a fixed lookback — usually 20 or 21 days — instead of an endless running total. That bounded range, roughly -1 to +1, fixes OBV's starting-value problem outright. CMF resets its own window all the time, instead of carrying one all-time running sum.
Money Flow Index (MFI). MFI goes further still. It brings in the real size of the price move — the "typical price," or high plus low plus close divided by three, times volume — into a 0–100 bounded line built on the same up/down logic as RSI. Because it weighs the size of the move, not just its sign, MFI fixes the one-tick problem that OBV cannot.
No single alternative is simply "better" in every situation. Each one trades away some of OBV's simplicity for a specific fix, and each introduces its own lookback-length sensitivity in exchange. What they share is this: none of them is read as an absolute level either — all three are read as slope, divergence, or threshold-crossing relative to a bounded range, which should tell you something about how volume indicators as a category are meant to be used.
Reading OBV Alongside Order Flow and Raw OHLCV
OBV is a derived, compressed summary of two raw inputs: closing price direction and traded volume. Before trusting a divergence reading, look at the underlying order flow that produced the volume figure in the first place. Look at the raw OHLCV data OBV is compressing, too. A single large block trade printed at the close can move OBV by the same amount as a day's worth of ordinary retail flow. The compressed line cannot tell you which one actually happened. The raw data underneath it can.
This is the practical argument for not reading OBV in isolation, on its own panel, disconnected from everything else on the chart. Inside the Quantzee AI Adaptive Quant Toolkit, OBV-style volume divergence logic is one input among several oscillator and trend-confirmation layers. It is not a standalone trigger, because a single volume-derived line, read alone, inherits every limitation described above. A related toolkit layer, the Adaptive AI Oscillation Engine, applies a comparable divergence-confirmation approach to momentum oscillators rather than volume. That is a useful cross-check when an OBV divergence shows up without a matching momentum divergence alongside it.
Quantzee builds analytical software for traders who want to study these relationships themselves. The toolkit surfaces the data and the divergence flags. It does not issue trade calls, and it does not carry any regulatory advisory registration of any kind. Every setting shown above, including the 20-day divergence window and any volume-filter cutoff, should be paper traded first on your own symbol and timeframe before it touches live capital.
A Worked Example: Same Price, Different OBV Read
Take a 40-day stretch where a stock's closing price moves from $82 to $91 — an 11% rally. In scenario one, the rally happens on rising volume each leg up. Volume peaks at 2.1x its 20-day average on the final push. OBV rises in a clean, accelerating slope across the same 40 days, confirming the move. In scenario two, the identical $82-to-$91 price path happens on volume that is flat-to-declining. Each successive up leg trades on slightly less volume than the last. Volume drops to 0.7x the 20-day average by the final push. OBV in scenario two still rises, because every day in the move was an up day. But the slope flattens noticeably in the back half.
Both scenarios show the exact same price chart. Only the OBV slope tells you which one happened. Scenario one is the textbook "healthy, volume-confirmed advance." Scenario two is the textbook setup analysts flag as vulnerable to a sharp reversal. The buying pressure behind the move was thinning out even as price kept printing new highs. That is the bearish OBV divergence pattern discussed above, just expressed as flattening slope rather than an outright lower high on OBV.
Common Reading Mistakes We See Most Often
In our own experience reviewing OBV setups with Quantzee toolkit users, a handful of mistakes repeat constantly. We list them here because naming the mistake is often enough to stop making it.
Reading the level, not the slope. This is the mistake the whole post is built around. A trader screenshots a chart with OBV at some large positive or negative number and asks whether that number is "good." It is not a meaningful question, for every reason covered above.
Trusting a divergence on a single symbol with no separate confirmation. Our own 94-case sample found roughly half of bullish divergences resolved bullishly within 20 days. Half did not. A single divergence, alone, is closer to a coin flip than a signal.
Comparing OBV across two different tickers. Because the starting value is arbitrary and the share count differs between any two stocks, there is no shared scale to compare against. OBV on Stock A and OBV on Stock B are not on the same axis, ever.
Ignoring the lookback window entirely. A 10-day slope and a 60-day slope on the same chart can point in opposite directions at the same time. Pick a lookback that matches your holding period, and be explicit about which one you are reading before you act on it.
The two questions worth asking about any OBV chart are these: is OBV's slope over my relevant lookback agreeing with price's slope, and is there a divergence between the two that has persisted for more than a handful of bars? Everything else about the indicator — the exact number on the axis, whether it sits above or below zero, whether it is higher than six months ago in absolute terms — is noise inherited from an arbitrary starting point that was never meant to carry meaning on its own.