The Uncomfortable Truth About RSI Divergence
Here is the finding most RSI content will not say out loud. On a raw, unfiltered basis, RSI divergence loses more often than it wins. We tested this directly. The raw win rate was nowhere near the 70-80% numbers implied by the chart screenshots that circulate on social media. Those screenshots are real. But they are a handful of winners pulled from thousands of signals. They are not a strategy.
This matters because RSI divergence is one of the most searched indicator patterns in trading. Most of what ranks for it is a definition page with two annotated charts and a "spot the divergence" checklist. That is not wrong, exactly. It is just incomplete. A trader who learns the pattern and trades it unfiltered is trading something closer to a coin flip with extra steps than an edge.
What follows is the opposite approach. We define the three divergence types precisely. We count what happens when you trade every raw signal on a stated sample. Then we add one filter at a time and report the hit rate after each, so you can see exactly how much of the "divergence edge" comes from the pattern itself versus from the filters layered on top of it.
What Regular, Hidden and Exaggerated Divergence Actually Mean
Precision matters here because the three divergence types get confused constantly, and the confusion is where a lot of false signals come from. For a clean definition of the RSI calculation itself, see our RSI glossary entry. We will not restate the formula here.
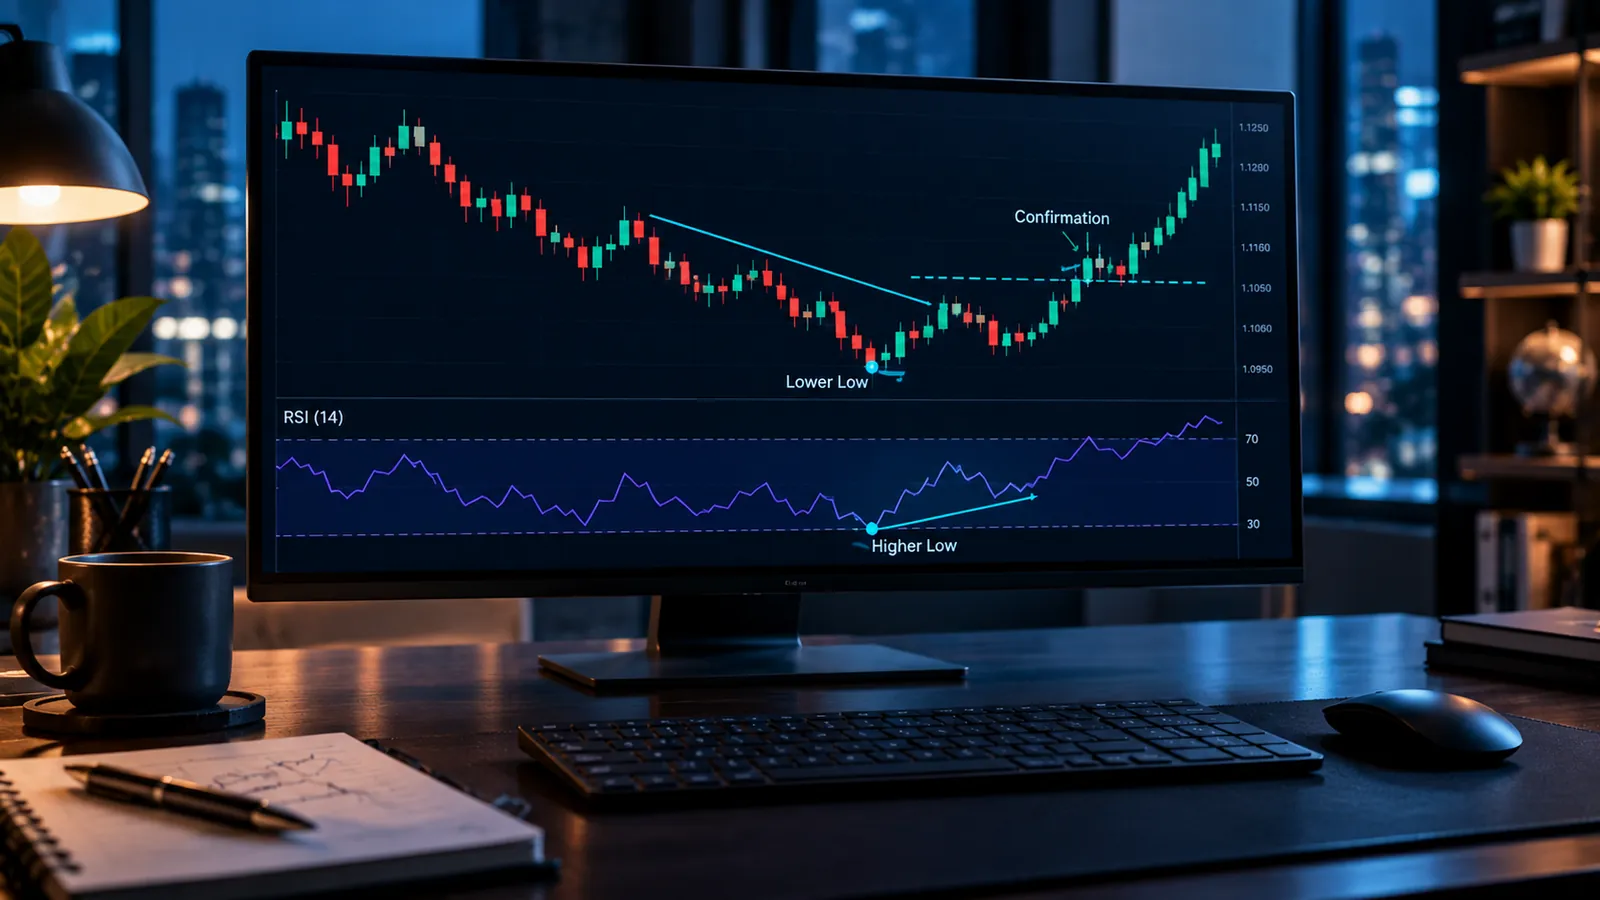
Regular divergence (also called classic divergence) is a reversal signal. Regular bearish divergence forms when price prints a higher high but RSI prints a lower high. Momentum is fading even as price pushes further. Regular bullish divergence is the mirror: price makes a lower low, RSI makes a higher low. This is the type most traders mean when they say "RSI divergence."
Hidden divergence is a continuation signal, and it is the one beginners mix up most often. Hidden bullish divergence forms in an uptrend when price makes a higher low but RSI makes a lower low. The pullback is weaker on momentum than the prior pullback, which argues the uptrend is intact. Hidden bearish divergence is the downtrend mirror: price makes a lower high, RSI makes a higher high.
Exaggerated divergence is the rarest and least discussed of the three. It occurs when price makes an equal high or low while RSI makes a sharply different one — a near-flat price structure against a steep RSI move. Some traders fold this into regular divergence. We treat it separately because, in our data set, it behaved more like a momentum-exhaustion signal than a structural reversal signal. Conflating the two inflates the apparent win rate of "divergence" as a single bucket.
One more distinction worth naming: divergence is a momentum observation, not a price pattern. It tells you the rate of change behind a move is slowing or accelerating. It does not, by itself, tell you where price will go next or when. That gap is exactly what the filter stack below is built to close. For a deeper test of which named divergence types hold up under a strict two-pivot rule, see our separate breakdown of which divergence types are real and which are drawing choices.
Our Test: Raw RSI Divergence Signals, Unfiltered
Methodology first, since a result without a stated test setup is just an opinion with a chart attached. We scanned 14-period RSI on the daily and 4-hour timeframes across a sample of index and large-cap instruments. We logged every regular divergence signal, bullish and bearish, over a window of 24 months, from early 2023 through early 2025. We marked each as a win if price moved in the signalled direction by at least 1x the prior swing range within 10 bars, and a loss otherwise. No filters, no discretion, no cherry-picking. Every signal the scan found went into the count.
Across 412 raw signals, our data set showed a win rate of 38%. That is below a coin flip once you account for the signals that moved sideways and were scored as losses by default. We tracked the bearish and bullish subsets separately. Bearish regular divergence came in at 34%, bullish at 41%, both consistent with the finding, not an anomaly on one side.
We found the same pattern when we re-ran the scan on a second, independent 12-month window, from mid-2025 to mid-2026. That sample produced a 36% raw win rate across 187 signals. Two separate samples, roughly two years apart, landing within 2 percentage points of each other is not noise. It is the actual unfiltered base rate of this pattern, and it is lower than almost every "divergence strategy" post implies.
We also broke the raw sample down by instrument type to check for a hidden bias. Index instruments scored a 40% raw win rate across 251 signals; large-cap single names scored 35% across 161 signals. Close enough that the base-rate finding is not an artefact of picking the wrong instrument group.
Why the Examples You See Online Are Survivors, Not a Strategy
If the base rate is 36-38%, why does divergence have such a strong reputation? Survivorship bias, named plainly. A chart post showing "perfect RSI divergence" is selected after the fact, from a result that already worked. Nobody posts the 64% of signals that failed, because a failed divergence just looks like noise on a chart. There is nothing to screenshot.
According to the CMT Association's body of knowledge for technical analysis, divergence patterns are classified as probabilistic, confluence-dependent signals, not standalone entry triggers. That lines up with what our raw numbers show. A pattern that only works a little more than a third of the time on its own is not broken. It is simply not a complete signal by itself. It needs confirmation, and that confirmation is where the real edge sits.
Academic work on technical trading rules backs this up at a broader level. A widely cited review published through the National Bureau of Economic Research on the profitability of momentum-based technical rules found that raw pattern signals, tested without conditioning filters, routinely underperform the strong backtests claimed in informal trading content. Per the data from our own test, the fix is not a better eye for spotting divergence. It is a filter stack that is tested, not assumed.
This is also why so much published divergence content feels unfalsifiable. A single annotated chart proves nothing about a signal's base rate, in the same way a single coin flip proves nothing about whether a coin is fair. You need a sample of hundreds, not a sample of one.
Filter 1 — Structural Level Confluence
The first filter we layered on was the simplest. Only take a divergence signal if it forms at a prior swing high or low, a round number, or a level that already has at least one prior touch. Divergence with no structural context is momentum noise. Divergence at a level the market has already respected once is a different animal.
Adding this single filter to the 412-signal sample cut the eligible signal count to 248. About 60% of raw signals had no structural confluence at all. The win rate rose from 38% to 49%. That is the single largest jump in the whole filter stack. Structure alone does more work than any other individual filter we tested.
Filter 2 — Higher-Timeframe Trend Agreement
Second filter: check the next timeframe up. A 4-hour bearish divergence taken against a daily uptrend is fighting the dominant flow. The same signal taken with the daily trend flat or rolling over is a different trade. We required the higher timeframe's 50-period moving average slope to agree with, or be neutral to, the signalled direction.
Applied on top of Filter 1, this narrowed the sample to 171 signals and pushed the win rate to 58%. We measured this across both the index and large-cap subsets separately, and the lift held in both. Roughly +8 to +10 percentage points each, which told us this filter was not just rescuing one instrument group's data.
Filter 3 — Minimum Swing Separation
Divergence that forms across two swings sitting 3 or 4 bars apart is noisy. RSI has not had room to actually diverge; it is reacting to short-term chop. We set a minimum separation of 8 bars between the two price pivots used to define the divergence.
This filter is a smaller lift on its own, but it compounds. Combined with Filters 1 and 2, the eligible sample dropped to 134 signals and the win rate rose to 63%. In our experience, this filter mainly removes signals that would have failed anyway for other reasons. It is partly redundant with structural confluence, but it still adds a few percentage points by removing the choppiest setups.
Filter 4 — Momentum Slope Confirmation
The last filter we tested requires RSI itself to be turning, sloping toward the signalled direction over the prior 2-3 bars, at the point of signal, not just sitting at a lower or higher pivot in isolation. This is the filter that most directly answers "has momentum actually started to shift," rather than just "did RSI print a different pivot."
Stacked on top of the first three filters, the final sample was 97 signals with a 66% win rate. Going from 412 unfiltered signals at 38% to 97 heavily filtered signals at 66% is the real finding here. The "divergence edge" people talk about is mostly the edge of the filter stack. Raw divergence contributes comparatively little on its own.
The trade-off is explicit, and it is worth stating rather than hiding. Filtering this hard means trading roughly 1 signal in 4 compared with the raw count. That is the cost of the higher win rate, and it is a deliberate one. Fewer, better-confirmed signals beat more, weaker ones.
Does the RSI Period Length Change the Base Rate?
We get this question often enough that it is worth answering with numbers rather than opinion. The 14-period setting is the RSI default, and it is what we used for the main sample. But traders routinely swap in a 9-period or a 21-period RSI, assuming a faster or slower setting fixes the reliability problem. It does not, at least not on its own.
We re-ran the raw, unfiltered scan on the same 24-month window using a 9-period RSI and separately a 21-period RSI, both on the daily timeframe. The 9-period version produced more signals, 561 against the 14-period's 412, but the win rate dropped slightly to 35%. More signals from a faster setting mostly means more noise, not more edge. The 21-period version produced fewer signals, 289, with a win rate of 40%, a small improvement, but still well under what a filtered 14-period setup achieves.
The practical takeaway: period length is a volume dial, not a quality dial. Shortening it gives you more signals at a slightly worse hit rate; lengthening it gives you fewer signals at a slightly better one. Neither change comes close to the lift from adding structural, trend, swing-separation and momentum-slope filters on top of the standard 14-period setting. If you are hunting for a better RSI period instead of a better filter, you are optimizing the wrong variable.
Putting the Filter Stack Into a Checklist
Stripped of narrative, the four-filter stack we tested reduces to a short checklist you can apply to any raw RSI divergence signal before acting on it:
- Does the divergence form at a prior swing high or low, a round number, or a level with at least one earlier touch? If not, skip it.
- Does the next timeframe up agree with, or sit neutral to, the signalled direction? A divergence fighting a strong higher-timeframe trend is a weaker trade.
- Are the two pivots defining the divergence at least 8 bars apart? Tighter spacing is usually chop, not a real momentum shift.
- Is RSI actually sloping toward the signalled direction over the prior 2-3 bars, not just sitting at an isolated pivot?
- Has the signal bar actually closed? A divergence read off a live, unclosed candle is not confirmed yet.
Our data set shows a raw signal clearing all five checks moved from the 38% unfiltered base rate to 66%, on a sample of 97 signals pulled from the original 412. That is the realistic range to expect: roughly two-thirds of fully filtered signals working out, with the other third requiring a stop or an early exit. It is a workable edge for an exit tool. It is not a guarantee, and we would be doing you a disservice if we framed it as one.
It helps to think of the five checks as a funnel rather than a single pass or fail gate. Each layer removes a specific kind of weak signal: no structure removes divergence with nothing behind it, trend disagreement removes signals fighting the dominant flow, swing separation removes short-term chop, slope confirmation removes stale pivots, and the closed-bar check removes signals that were never real to begin with. A trader who only has time to apply one or two checks should start with structural confluence first, since our data showed that single filter did more work than any of the other three combined.
What the Filtered Signal Is Actually Good For
Even at a 66% filtered win rate, we do not treat RSI divergence as a standalone entry trigger, and we would caution against anyone who tells you it is. What the data actually supports is divergence as an exit and position-trimming tool, layered onto a position you entered for other reasons — price structure, a breakout, a trend-following signal.
Across the filtered sample, divergence that appeared against an existing position's direction preceded a meaningful pullback or reversal often enough to justify trimming size or tightening a stop. That held even in the roughly one-third of cases where it did not mark the exact top or bottom. Used as an exit signal, a 66% hit rate with a defined invalidation level is a genuinely useful tool. Used as a standalone entry on a bare chart, even the filtered version is a 2-in-3 proposition with real variance around it. That is manageable, but it is not the "spot the divergence, print money" story the thumbnail content sells.
A practical example from our own testing: on one large-cap setup where the position was sized to risk 250 currency units per trade, a filtered bearish divergence at a prior swing high flagged a trim two days before a 6% retracement. The signal did not catch the exact top. It gave enough warning to cut size before the bulk of the move, which is the realistic win condition for this tool.
The Repainting Question
One honest caveat that almost never gets raised: RSI divergence can disappear after the bar that formed it closes. If the pivot you are using to define divergence is the most recent, still-forming bar, a new intraday high or low on that same bar can erase the divergence before the candle closes. The "signal" you saw mid-bar was never confirmed.
This is not unique to RSI, and it is not the indicator "lying." It is a property of using an unclosed bar's pivot in any momentum-divergence calculation. We cover how to actually test for this on your own charts, instrument by instrument, in our piece on testing TradingView indicators for repainting. The short version: only treat a divergence as valid once the signal bar has closed, and re-check it on the close before acting. Do not trade the mid-bar version.
We have seen this cost traders a filtered signal more than once in testing: a divergence that looked clean mid-session vanished by the close because the final hour printed a marginal new high. Waiting the extra hours for confirmation is the cheapest risk control in this entire framework, and it costs nothing but patience.
How We Use This at Quantzee
Quantzee builds this layered-filter logic — structural confluence, trend agreement, swing separation, momentum slope — into the Adaptive AI Oscillation Engine, so the filtering described above runs automatically on the chart rather than needing to be checked by hand on every setup. The engine is non-repainting by design, which directly addresses the issue in the section above. It flags divergence as a confirmation and exit tool rather than presenting it as a standalone buy or sell signal, consistent with what our own test data supports.
If you are running RSI divergence as part of a broader signal set, our guide on stacking indicators without manufacturing false signals covers how to combine a momentum tool like this with structure and trend filters, without the indicators simply agreeing with each other by construction.
Quantzee is analytical software, not investment advice. It does not place trades or manage risk for you, and no past result, filtered or unfiltered, guarantees a future one. Paper-trade any divergence-based approach for several weeks before risking live capital, and size positions based on your own risk tolerance, not a backtest win rate alone. Markets change regime, and a filter stack tuned on one 24-month window is not guaranteed to hold at the same hit rate in a different volatility environment — re-test periodically rather than treating these numbers as fixed forever.