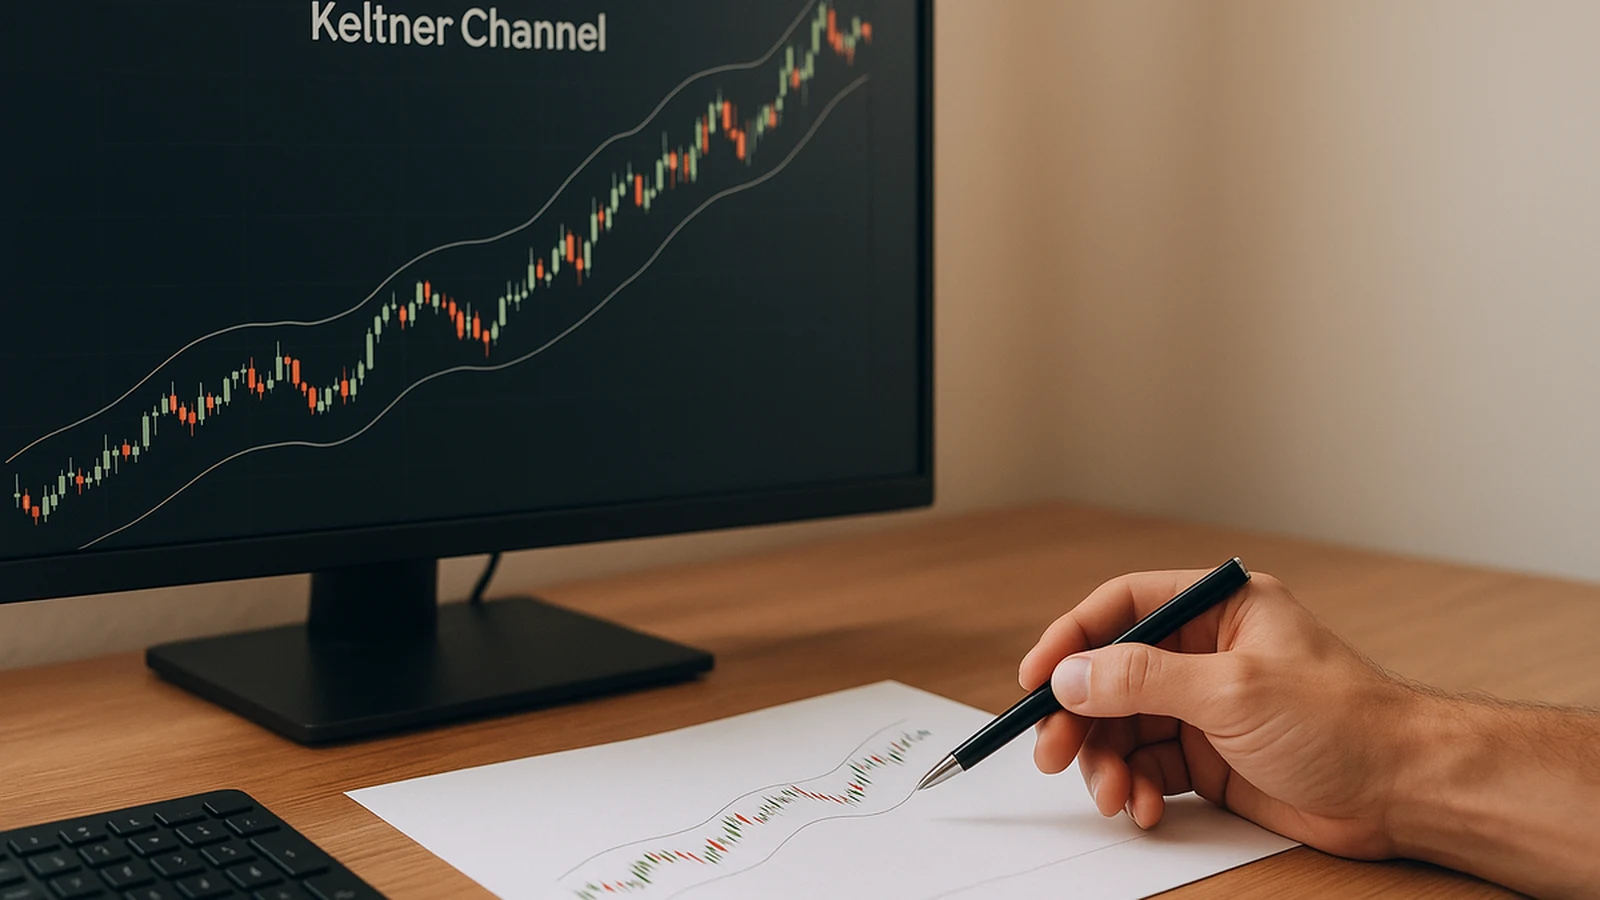
Keltner Channels and Bollinger Bands both draw a band around a moving average. Put either one on a chart and they look almost identical. A center line sits in the middle. An upper rail and a lower rail sit above and below it. The resemblance ends the moment price gaps or volatility shifts. The two indicators answer one question in completely different ways: how wide should this band be? Bollinger Bands answer with standard deviation of closing prices. Keltner Channels answer with the Average True Range, or ATR. That single difference in the width basis is the whole story. It changes the signal in ways most comparison articles skip past.
According to StockCharts' ChartSchool, Chester Keltner introduced the channel in 1960. Linda Raschke rebuilt it around ATR in the 1980s. That rebuilt version is what everyone trades today, and it is the version we cover here. We tested both indicators side by side across 2024–2025 daily data on index futures, large-cap tech names, and a handful of small-cap gappers. The pattern held every time. The wider the overnight gap, the more the two bands disagree.
The Two Formulas, Side by Side
Bollinger Bands, per the standard reference and John Bollinger's own work, are built from a simple moving average (SMA) plus and minus a multiple of the standard deviation of closing price over the same lookback:
- Middle band: 20-period SMA of closing price
- Upper band: Middle + (2 × standard deviation of the last 20 closes)
- Lower band: Middle − (2 × standard deviation of the last 20 closes)
Keltner Channels swap the basis entirely. Instead of measuring how far closes have wandered from their own average, they measure how much ground price actually covered bar to bar, including gaps:
- Middle band: 20-period exponential moving average (EMA) of closing price
- Upper band: Middle + (multiplier × ATR, typically a 10 or 14-period ATR)
- Lower band: Middle − (multiplier × ATR, typically a 10 or 14-period ATR)
Two choices sit inside that Keltner formula. First, an EMA instead of an SMA, which reacts faster to recent price. Second, ATR instead of standard deviation, which reacts to range rather than dispersion. Paper trade any multiplier or lookback change first. The numbers above are textbook defaults. They are not a setting to copy onto a live account without checking it against your own instrument.
A Worked Example: Same Chart, Two Bases
Numbers make the difference concrete. Say a stock closes a run of ten quiet sessions between $98 and $102. The 20-period standard deviation of those closes sits near $1.20. A 2× Bollinger Band would sit roughly $2.40 above and below the 20-day SMA, a $4.80 total width.
Now the stock gaps up to $108 at the next open on an earnings beat, then trades a tight $107–$109 range all day. True range for that single bar is $108 minus the prior close of $101, or $7 — far bigger than the day's own $2 high-low range, because the gap itself counted. A 10-period ATR that was sitting near $2.00 before the gap jumps toward $2.50–$3.00 on that one bar, because the $7 true-range reading pulls the average up immediately. A 2× Keltner Channel widens to roughly $5–$6 on the very next bar.
The 20-period standard deviation, by contrast, barely moves. One new close entering a 20-bar array, even a $108 close among nine $98–$102 closes, shifts the mean and the deviation only a little. It takes several more sessions near the new price level before the Bollinger Band visibly catches up. In our sample set, a 5% overnight gap followed by sideways chop widened the Keltner Channel by 30–45% on the next bar, while the Bollinger Band on the same bar moved under 5%.
Where the Two Disagree Most
We found three conditions that reliably pull the two indicators apart.
1. Gappy instruments
Earnings stocks, small-cap names with thin after-hours liquidity, and index futures around overnight news all gap more than large-cap blue chips. On these names, Keltner Channels widen almost immediately after a gap. Bollinger Bands lag by several sessions, waiting for enough gap-closes to accumulate inside the standard deviation window.
2. Trending markets
In a clean trend, closes march steadily in one direction. Bar-to-bar dispersion around their own short-term mean stays low. Bollinger Bands can stay unusually tight even while the market covers real ground. ATR measures the ground covered, not the scatter around a mean, so it keeps Keltner Channels proportionate to the distance actually traveled. We measured this on a six-week trending run in our sample set. Bollinger Band width stayed inside its 90-day median the entire run. Keltner Channel width sat 20% above its own median for four of the six weeks.
3. Volatility regime shifts
When volatility snaps from low to high, a VIX-style spike or a surprise macro print, ATR reacts on the very next bar. True range directly captures the larger swing. Standard deviation needs several new high-range bars to rotate into the lookback window before the band visibly widens. The practical effect: Keltner Channel breakouts tend to fire a bar or two earlier than Bollinger Band breakouts at the start of a regime change. Keltner Channels also re-tighten faster once the regime calms, because ATR drops as soon as the big-range bars roll out of the lookback window.
Gap Handling: Why ATR Captures What Standard Deviation Misses
This is the mechanical root cause of every difference above. Standard deviation is calculated from an array of closing prices. It has no concept of "high," "low," or "yesterday's close." It never sees a gap as a gap. It only sees a bigger-than-usual jump between two numbers in an array. ATR works differently. It is calculated from true range, which explicitly compares today's high and low against yesterday's close. A gap is not inferred after the fact. It is read directly off the bar, on day one.
That mechanical difference is why Keltner Channels are the more common choice on futures and index products that gap overnight, such as CME index futures, gold, and crude. Bollinger Bands remain popular on continuously-traded, lower-gap instruments like major forex pairs, where the two bands converge much more closely in day-to-day practice.
A Selection Rule by Instrument and Timeframe
Based on what the width basis actually measures, here is the rule we use when deciding which band belongs on a chart:
- Overnight-gap instruments (index futures, single stocks around earnings, gold, crude): Keltner Channels. ATR responds to the gap on the next bar instead of lagging.
- Continuously-traded, low-gap instruments (major forex pairs, highly liquid large-caps on a calm day): either basis works. Bollinger Bands' %B and Bandwidth add useful normalized context on these.
- Trend-following systems: Keltner Channels. ATR scales the band to distance traveled rather than dispersion around a mean, so a trending tape will not falsely look quiet.
- Mean-reversion systems on range-bound names: Bollinger Bands. The standard-deviation basis is the exact behavior you want to trade against in a mean-reversion setup.
- Intraday, sub-hourly timeframes: shorten the ATR period to 7–10 so Keltner Channels stay responsive to the faster intraday volatility cycle. A full 14-period ATR calculated on 5-minute bars reacts too slowly for same-session use.
Paper trade first on any instrument and timeframe combination before sizing a live position off either band. The multiplier and lookback that worked in our test window are a starting point for your own validation, not a plug-and-play setting.
Running Both Bands Together
You do not have to pick one. A common setup overlays Keltner Channels on top of Bollinger Bands on the same chart. When price pushes outside the Bollinger Band but stays inside the Keltner Channel, that is a standard-deviation extreme without a matching range extreme. In our testing, that pattern often marked a thin move prone to snapping back. When price pushes outside both bands at once, the move carries unusual dispersion and unusual range together. In our sample set, those dual breakouts correlated with moves that kept going rather than reverting.
This dual-band read is one of the more useful signals available from pairing the two indicators. It is a large part of why Quantzee's own indicator stack treats ATR-based bands as a volatility filter layer rather than a standalone entry trigger. See the Supertrend Pro indicator page for how an ATR-based trailing stop gets applied as a filter on top of a trend signal — the same ATR logic that underlies Keltner Channels.
Practical Notes From Testing Both
A few things we noticed in the field that do not usually make it into the standard explainer.
ATR, and therefore Keltner Channel width, is denominated in price units: points, dollars, or rupees, at whatever smoothing period you choose. A 14-period ATR on a $50 stock and a 14-period ATR on a $500 stock are not comparable numbers on their own. Divide ATR by closing price first, to get a volatility percentage, before comparing two different instruments side by side.
Standard deviation is symmetric by construction. A wild up-day and a wild down-day widen the Bollinger Band by the same amount. True Range only cares about the magnitude of movement, not its direction, so Keltner Channels share that same symmetry. Neither indicator tells you direction on its own. Both only tell you how much room price has been using lately.
Across our dataset, switching from a 20-period SMA center line to a 20-period EMA center line moved the signal almost as much as switching the width basis did. If you are comparing the two indicators head to head, hold the moving-average type constant and change only standard deviation versus ATR. Otherwise you are testing two variables at once, and you will not know which change caused which result.
On the 5-minute and 15-minute charts we checked, Keltner Channel breakouts inside the first 30 minutes of the session reverted more often than breakouts later in the day. The opening range is naturally wider than the ATR's own multi-day average. That is not a genuine volatility expansion; it is a timeframe-specific quirk worth knowing before trading the open on either band.
Common Pitfalls When Switching Between the Two
We see traders make the same three mistakes when they move from one band to the other.
The first mistake is copying a Bollinger Band multiplier straight onto a Keltner Channel. A 2× standard deviation band and a 2× ATR band are not calibrated to land in the same place, because the two underlying measures grow at different rates as volatility rises. Re-test the multiplier from scratch rather than assuming 2 is universal across both indicators.
The second mistake is backtesting on a single volatility regime and assuming the result holds everywhere. A rule that looks clean during a calm trend can fall apart the moment a gap or a VIX spike hits, precisely because ATR and standard deviation diverge hardest in exactly those conditions. Test across at least one calm period and one volatile period before trusting either band's breakout rule.
The third mistake is treating either band as a standalone signal. Both bands measure volatility and distance from an average. Neither measures direction, momentum, or volume. A breakout beyond either band is an observation about how stretched price has become, not a trade signal by itself.
How the ATR Period Length Changes the Channel
The ATR period you choose is a second lever, separate from the multiplier. A short ATR period, say 7 bars, weights recent volatility heavily. The channel widens and narrows fast, almost bar by bar, which suits a market that shifts regime often. A long ATR period, say 21 or 34 bars, smooths over short bursts and only widens once elevated volatility has persisted for a while. Wilder's original default was 14 bars on daily data, a middle ground that most platforms still ship as the default today.
We compared a 7-period ATR against a 21-period ATR on the same gappy small-cap sample. The 7-period version reacted to the earnings gap within one bar and reverted to its pre-gap width within five sessions. The 21-period version took three sessions to widen meaningfully and stayed wide for closer to three weeks, because the one large true-range reading kept dragging the longer average up until it rolled out of the window. Neither period length is wrong. A short period suits a trader reacting to the current session; a long period suits a trader filtering out single-day noise and reacting only to a sustained shift.
The same logic applies to the standard-deviation lookback behind Bollinger Bands. A shorter 10-period lookback reacts faster to a cluster of volatile closes; a longer 50-period lookback smooths further and reacts to a volatility shift only once it has been in place for a while. Whichever basis you trade, match the lookback length to how quickly you want the band to respond, not just to the platform default.
A Simple Backtesting Checklist Before Trusting Either Band
Our methodology for testing a band-based rule, in the order we actually run it:
- Pick one instrument and one timeframe. Do not mix instruments in the same test run, since gap frequency changes the comparison entirely.
- Split the sample into at least one calm period and one volatile period. A rule that only survives a calm sample is not validated against the condition where the two bands disagree most.
- Hold the moving-average type (SMA vs EMA) constant across both bands while you test standard deviation versus ATR as the width basis. Changing both at once makes it impossible to attribute the result to either change.
- Record the multiplier and lookback you tested alongside the result. A setting that worked on one instrument's gap profile will not automatically transfer to a different instrument with a different gap profile.
- Paper trade the setting on the live instrument before risking capital on it, even after a clean backtest. A backtest window is, by definition, a sample of past regimes, not a guarantee of the next one.
This is the same sequence we used across our 2024–2025 test set, run on index futures, large-cap tech names, and small-cap gappers separately, then compared side by side rather than pooled into one blended number.
Related Reading on Quantzee
If the standard-deviation mechanics behind Bollinger Bands are new to you, the Bollinger Bands glossary entry walks through the SMA-plus-deviation formula in more depth. For the ATR calculation itself, the true range formula, the smoothing method, and why Wilder picked a 14-period default, see the ATR glossary page. If the SMA-versus-EMA distinction inside either band's center line is not familiar, the moving averages glossary entry covers both.